
Marktanalysen
Who Develops in Zanzibar: The Operator Map
Zanzibar has no register of developers. It has an investment authority that issues certificates, a land regime built on leases, and, since April 2025, a trade association. This note maps the operators that can be named from public sources, what each is documented to have built and where, and the tests an allocator can use to tell a developer from an intermediary. Every name carries its source. Every gap is disclosed.
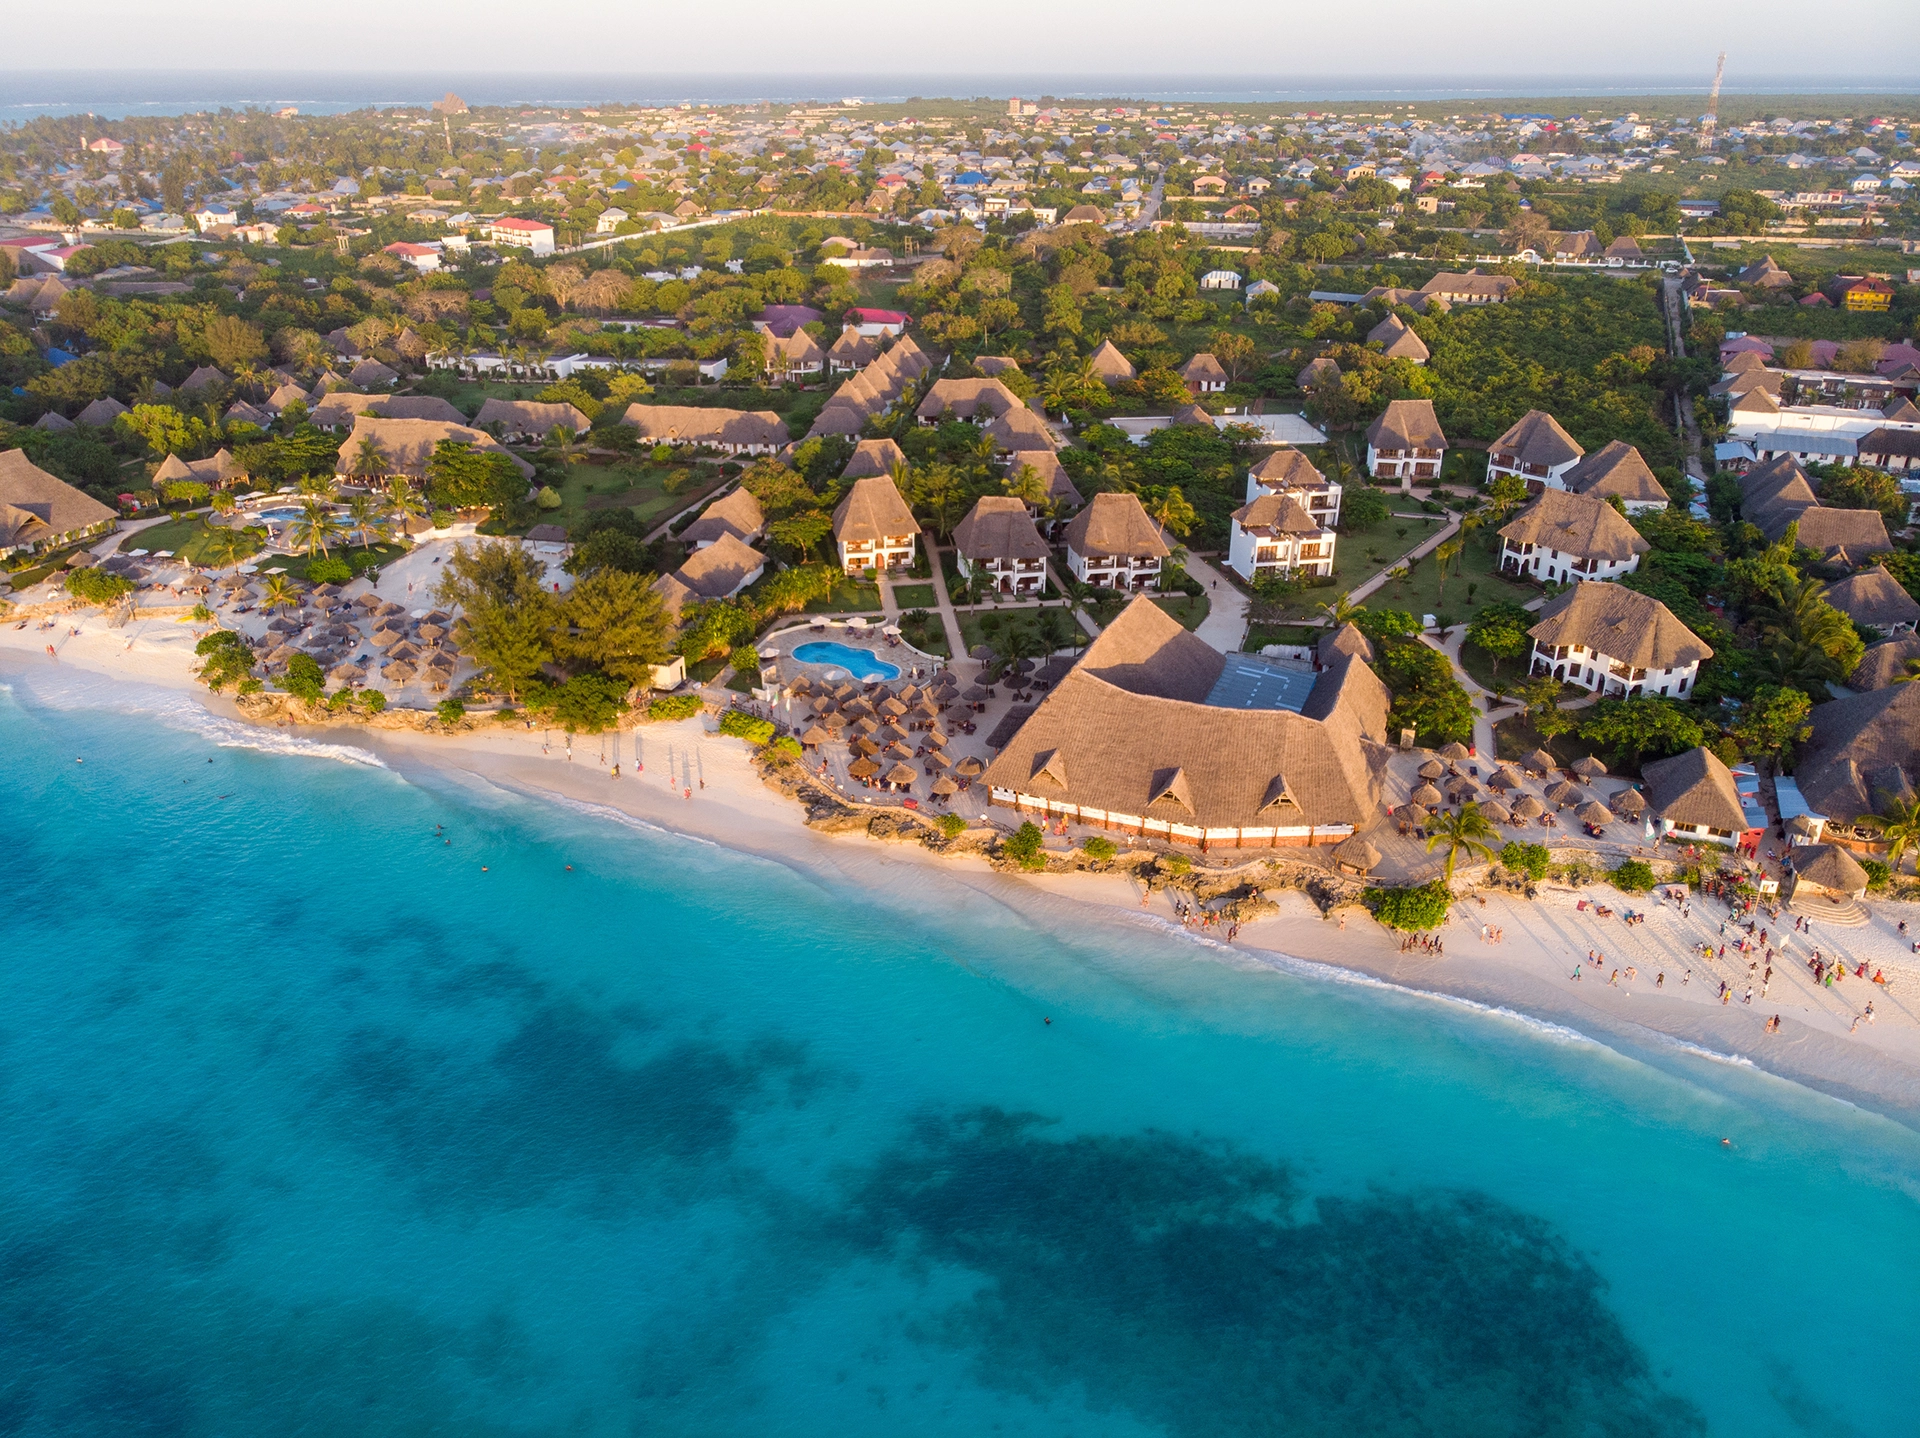
The Question Has No Official Answer
Zanzibar publishes no list of licensed property developers. There is no register an allocator can query to see who holds land, who holds a permit and who has delivered. What exists is a set of partial records. The Zanzibar Investment Promotion Authority (ZIPA) issues Certificates of Investment. The land ministry issues leases. Neither publishes a consolidated developer roster that we could find.
So the map has to be built from the outside. That means company disclosures, trade press, the new trade association's own pages, and court and arbitration records where a project went wrong. Each source has a different reliability. A developer's own website tells you what it wants known. A press report tells you what a journalist could confirm. An arbitration filing tells you what someone was willing to litigate.
This note grades every claim accordingly. Company-stated means the operator says it. Press-reported means a named outlet reported it. Documented means an official or court record exists. Where sources disagree, we say so rather than choose the tidier number.
This is a map of the sector, not a ranking. We do not score operators, and we do not recommend any of them. Victaura's parent holds a position in prime resort property, which is why the ordering below follows evidence quality, not relationship.
The Legal Frame That Defines a Developer
On Zanzibar, a foreign developer is a lessee, not an owner. According to legal commentary summarising the Land Tenure Act 1992, foreigners cannot own land outright. The Act allows land to be leased to any person, Zanzibari or not, for investment purposes, subject to approval of the project by ZIPA or another relevant authority. Buyers of finished homes typically receive a long leasehold. The standard term reported for Fumba Town is 99 years, with rental, sale, mortgage and inheritance rights.
The investment threshold sits high for hotels and real estate. ZIPA's regulatory portal states a minimum capital investment of $2,500,000 for foreign investors in the hotel and real estate sectors, and $300,000 for local investors. That is the published entry ticket for a foreign developer, and it is a measured, official figure. It filters out the smallest speculative schemes, at least on paper.
The path runs through ZIPA first. The portal describes ZIPA as a one-stop centre. The investor obtains a Certificate of Investment at project inception, and an Investment Service License after one year of operations, renewable annually. Lease agreements appear on the same portal as a separate procedure, and the document gives no detail on how that step works. That gap between the investment permit and the land lease is where the sector's largest documented failure occurred, discussed below.
A note on what is not stated here. Secondary guides describe a residence permit for buyers of ZIPA-approved property valued at $100,000 or more. We treat that as broker-reported until confirmed against a primary ZIPA instrument. It affects demand, not the definition of a developer.
The Association Now Exists
Zanzibar's first real estate developers' association launched on 3 April 2025. The Real Estate Developers Association, REDA, states an official launch date of 3 April 2025 at the Golden Tulip Airport Hotel. A Tanzanian daily, The Guardian, reported the launch under a headline describing a body billed to reinforce investment in Zanzibar. This is the closest thing the island has to an industry register, and it is very young.
Its stated agenda is regulatory, not commercial. REDA's own pages list aims that include improving the regulatory framework for real estate investment, permanent dialogue with the Zanzibar government, collaboration with urban planning authorities, ethical vetting of investors, sustainable construction practices, and know-how exchange with international associations. The launch coverage put the central grievance plainly as inconsistency in existing laws and in the overall framework for developers.
Membership is not a certification. REDA's site names member companies whose projects it showcases, among them CPS, PADDCO, Al Husseini Construction, Furaha Investment, PGH Company, Zanzibar Invest Group and LZDM. It also references a membership form open to architects, contractors, capital providers and investors. The site does not publish a member count, a membership test or an enforceable code. Belonging to REDA tells an allocator that a firm chose to join. It does not tell them the firm has delivered.
Public sources disagree on who sits where. The association's own page and a broker's write-up of the launch list different office-holders. Press coverage also names six member companies, including Johari Developers (Sandbank Villas), CPS (Fumba Town), Infinity Developers (Anantara Zanzibar), MB Homes, Mystique and Paddco. Because these lists do not match, we name companies and leave individuals out. Anyone relying on a roster should ask REDA for the current one in writing.
An association that has existed for a year can convene the sector. It cannot yet vouch for it.
Victaura Research
CPS Africa and Fumba Town: The Master-Planned Anchor
CPS Africa is the operator with the longest public delivery record on the island. A German engineering firm, it proposed Fumba Town to ZIPA and was granted a 99-year lease with rental, sale, mortgage and inheritance rights, according to the public encyclopaedic record of the project. Fumba sits inside a Free Economic Zone declared in 1992. Ground was broken in 2017 and the first houses were completed in 2018.
The delivery numbers are reported, and they vary by source. The same public record reports about 700 units completed by 2023 and about 800 by late 2025, with roughly 1,400 units sold and around 1,500 residents. Sold and completed are different things, and a gap between 1,400 sold and 800 completed is normal for an off-plan model. It is also exactly the gap an allocator should ask about. These figures trace back largely to company statements, so we grade them directional.
CPS now markets more than Fumba. Its website lists ten named developments, mostly in Fumba Town, plus a beach village in Paje. Entry prices on the site run from roughly $50,900 for family apartments to roughly $456,900 for villas. Those are asking prices from the operator, not transaction data. The site also carries return claims of 10 to 15 percent. We do not repeat those as findings, because no methodology is disclosed.
Infinity, Johari and PADDCO: The Resort and Villa Operators
Infinity Developments describes itself as Zanzibar's largest private developer. It is a subsidiary of Dubai-based Infinity Group. A March 2026 branded article on CNBC Africa states a portfolio of over $600 million in gross development value, including the Anantara Zanzibar Resort, Anantara Stone Town, an NH Collection property on Pemba and Infinity Hills, described as the largest gated residential community on the island. The article is labelled as partner content and gives no delivery timelines. The $600 million is company-stated.
The flagship has an independent press trail. The Anantara Zanzibar Resort at Nungwi has been reported in the trade and national press as a $230 million project, with one trade outlet reporting 111 keys. The developer partners with a global hospitality brand, which means the operating risk is shared with a branded operator. Whether a given phase is open or under construction should be checked against the operator's current announcements. We have not verified opening status.
Johari Developers is the villa-scale specialist. Its Sandbank Villas scheme at Nungwi is described on the company's site as 20 beachfront villas on 5,150 square metres, with Phase 1 fully reserved and an opening targeted for December 2025. That is company-stated and, at the time of writing, we have not confirmed handover. A broker's marketing note adds that the group is vertically integrated, with an affiliated contractor. Vertical integration can lower coordination risk and concentrate counterparty risk in the same place.
PADDCO is a Stone Town-based developer and REDA member. Its REDA profile lists a Malindi address and two developments, Chukwani Shores and BluPearl Nungwi, and claims more than a decade of experience. The profile gives no unit counts, completion dates or delivery evidence. We list it as active and unverified on output.
| Operator | Publicly reported projects | Where | Evidence grade |
|---|---|---|---|
| CPS Africa | Fumba Town and a Paje development; ten named schemes on its site | Fumba (Free Economic Zone), Paje | Reported and company-stated; longest public record |
| Infinity Developments | Anantara Zanzibar Resort, Anantara Stone Town, NH Collection (Pemba), Infinity Hills | Nungwi, Stone Town, Pemba | Company-stated; flagship also press-reported |
| Johari Developers | Sandbank Villas, 20 beachfront villas; Johari Beach Residences | Nungwi | Company-stated; handover not confirmed |
| PADDCO | Chukwani Shores; BluPearl Nungwi | Chukwani, Nungwi | Company-stated; no delivery data |
| Pennyroyal Ltd | Blue Amber Resort, lease terminated in 2022; ICSID claim registered in 2023 | Matemwe | Documented dispute; not delivered |
| Other REDA showcase members (Furaha Investment, PGH, Zanzibar Invest Group, LZDM, Al Husseini Construction) | Listed on REDA's site; not verified in this note | Not verified | Association listing only |
The Case That Defines the Risk: Blue Amber
The sector's most documented failure is a permit that outlived its lease. Pennyroyal, a British developer, held roughly 411 hectares at Matemwe on a leasehold dating from 2014, according to press reports, though one outlet gives 441. Its Blue Amber Resort was valued at $1.6 billion at completion, and the developer had invested about $55 million when the Ministry of Lands terminated the lease in early 2022. ZIPA then said the building permit could not be renewed.
Buyers were caught in the middle. The Citizen reported first-phase villa prices of $240,000 to $600,000, with some buyers having paid up to 90 percent before the suspension. A government minister was quoted saying the lease had been suspended while the developer still held its investment permit as the case proceeded. Two agencies, two documents, and no single reconciled position. That is the structural lesson.
The dispute went international and remains unresolved in the sources we found. The developer filed a claim at ICSID in July 2023. Proceedings were suspended twice for talks. The second suspension expired on 12 January 2025 without an agreement, and The Citizen reported the parties heading back to ICSID. We found no final award in public sources. Anyone reading this later should check the ICSID docket directly.
The government's own framing is worth reading carefully. The Zanzibar president was quoted as saying the termination resulted from a land dispute. A senior official also warned that the cancellation could affect investor readiness to come to the islands. We take no side on the merits, which are being arbitrated. The point for an allocator is narrower. An investment certificate is not title, and the developer's counterparty risk includes the state.
On Zanzibar the investment certificate and the land lease are two different documents. Underwrite both.
Victaura Research
Developer or Intermediary: Five Tests
A developer is the party that holds the lease and carries the construction risk. An intermediary sells, lists or markets units that someone else built. On an island where most buyers are foreign and remote, the two are easy to confuse, because both speak the language of projects and returns. The distinction decides who the buyer's counterparty actually is.
Test one is the lessee of record. Ask who holds the lease and the ZIPA Certificate of Investment for the specific plot. A developer can name both. An agent will name the developer. The documents should carry the same entity name, and the buyer's contract should be with that entity or a disclosed project vehicle.
Test two is the construction contract. Ask who signs with the contractor and who pays for delay. Developers hold that contract, or own the contractor. Intermediaries point to a third party. If the contractor is affiliated, treat the affiliation as a disclosed related-party position, not as a selling point.
Test three is delivered output, counted in handovers. Ask for completed and handed-over units with dates, not units sold or reserved. The Fumba figures above show why the two numbers differ. A developer with a delivery record can supply the count. A marketer will supply a pipeline.
Test four is the sales channel and its economics. Ask whether inventory is sold direct or through agents, and what the commission is. Agents are legitimate, but a listing platform or an agency blog is marketing, not an independent source. Several of the operator descriptions we found online sit on agency sites, and we graded them accordingly.
Test five is the association, used correctly. REDA membership is a signal of participation, not of solvency. Use it to find operators, then verify each one through the four tests above. The association itself states that it aims to set ethics and transparency guidelines, which is a stated aim, not yet a track record.
What This Map Does Not Show
The map is incomplete, and the missing part is probably the largest. Small local builders, family-owned schemes and off-market land holders do not appear in company press or association pages. Zanzibar's real developer population is larger than any list we can source. Most of it is unrated.
Activity data is thin. A secondary source reports that foreign buyers of property rose 20 percent in 2024, citing ZIPA-tracked transactions, with Gulf, German, Polish and South African nationals topping the list. We could not locate the underlying ZIPA release, so we do not use the figure as a finding. It is broker-reported.
Delivery is the thinnest column. Almost every unit count in this note is company-stated. Independent completion audits do not appear to exist for the island's private schemes. Until they do, an allocator has to build their own evidence, through site visits, handover certificates and buyer references.
Regulation is moving, and this note is a snapshot. The Zanzibar Investment Act 2023 is described in secondary guides as the governing framework for registration and incentives. We relied on ZIPA's regulatory portal for the capital thresholds, and we have not audited whether every project meets them. Any figure here should be re-verified before a decision, and the trade association's roster is likely to change as it matures.
Reading the Map as an Allocator
Sort operators by what has been handed over, not by what has been announced. On current public evidence, CPS has the longest visible delivery trail, resort operators such as Infinity have the largest announced pipeline, and villa specialists such as Johari sit at smaller scale with recent openings targeted. That ordering is about evidence, not quality.
Price the state as a counterparty. Blue Amber shows that permit, lease and political support can diverge. The remedy is diligence on the lease chain and on the ZIPA certificate for the specific plot, before deposit, not after.
Treat the new association as an information source and a pressure point. REDA can push for consistent rules and can make the sector easier to map. It should be watched for whether it publishes a member roster, admission criteria and a code with consequences. Each would raise its evidential weight.
Skin in the game disclosure. Victaura, through its parent Greystone B.V. (Netherlands), holds an active operating position in prime resort property. Readers should assume commentary may be influenced by, or benefit, Greystone's position. This document is classified as marketing material under MiFID II Article 24(3). It is not investment advice.
Wichtigste Erkenntnisse
- - Zanzibar has no published register of licensed developers; ZIPA issues investment certificates and the land ministry issues leases, so any map must be assembled from company, press and association sources (ZIPA; eRegulations Zanzibar).
- - Foreigners cannot own land under the Land Tenure Act 1992 and instead hold leases for approved investment projects; Fumba Town's lease is reported at 99 years (Wikipedia, Fumba Town; legal commentary on the Act).
- - The published minimum capital for foreign hotel and real estate investment is $2,500,000, against $300,000 for local investors (eRegulations Zanzibar, Services to investors).
- - The Real Estate Developers Association (REDA) launched on 3 April 2025; it publishes no member count or admission test, and public rosters of its office-holders disagree (REDA Zanzibar; The Guardian, 4 April 2025).
- - CPS Africa has the longest public delivery record: ground broken 2017, first homes 2018, roughly 800 units completed and 1,400 sold by late 2025, all largely company-derived and directional (Wikipedia, Fumba Town; CPS Africa).
- - Infinity Developments claims over $600 million in gross development value; the figure is company-stated in partner content and unverified (CNBC Africa, March 2026).
- - Blue Amber shows the permit-versus-lease gap: about $55 million invested against $1.6 billion projected value when the lease was terminated in 2022, and an ICSID claim registered in July 2023 with no final award found (The Citizen; Daily Maverick).
- - Distinguish developer from intermediary through five tests: lessee of record, construction contract, handed-over units, sales channel economics and association membership as a signal only (Victaura Research method).
Quellenangaben
- REDA Zanzibar, Home page
- REDA Zanzibar, About Us
- REDA Zanzibar, PADDCO member profile
- The Guardian (Tanzania), Real estate developers' body billed to reinforce investment in Zanzibar, 4 April 2025
- The Property Hub, Decoding REDA (broker commentary)
- The Property Hub, Top 4 Property Developments to Watch in Zanzibar 2026 (broker marketing)
- Wikipedia, Fumba Town
- CPS Africa, Company website
- CNBC Africa (partner content), Infinity Developments, March 2026
- Construction Week Online, Infinity Developments launches 111-key Anantara Zanzibar
- The Guardian (Tanzania), Anantara Zanzibar Resort, 5 September 2024
- Johari Developers, Sandbank Villas
- eRegulations Zanzibar, Services to investors
- Zanzibar Investment Promotion Authority (ZIPA)
- The Citizen, Shock waves hit Zanzibar's nascent real estate industry, 2022
- The Citizen, Tanzania, British developer head back to ICSID after stalled talks, January 2025
- Daily Maverick, Zanzibar revokes property lease for UK developer, 15 October 2023
- Global Arbitration Review, Tanzania taken to ICSID over island resort
Die Informationen auf dieser Website dienen ausschließlich zu Informationszwecken und stellen weder ein Angebot noch eine Aufforderung zur Abgabe eines Angebots noch eine Finanz- oder Anlageberatung dar. Angegebene Renditen sind Schätzungen und werden nicht garantiert; die Wertentwicklung in der Vergangenheit ist kein Indikator für zukünftige Ergebnisse. Das investierte Kapital ist einem Verlustrisiko ausgesetzt.
Erwägen Sie eine Investition in Luxusimmobilien an den Standorten, an denen wir tätig sind? Sprechen Sie mit uns über unsere aktuellen und kommenden Projekte.
Sprechen Sie mit Victaura →Weitere Insights
Destinationen
Zanzibar Beyond the Million: A Market Matures
Zanzibar recorded 917,167 international arrivals in 2025 on the official OCGS archipelago series and made July 2026 the strongest single month in its recorded history. The number that mattered to the frontier thesis has now arrived, and the arrival changes the underwriting. Three things reprice when the volume is real: the frontier discount compresses, infrastructure becomes an input rather than a footnote, and the luxury tier separates from the mass-beach product it was once bracketed with. This is a maturation print, not a maturity certificate, and the distinction is the whole allocation question.
Destinationen
Zanzibar: An Emerging Luxury Destination
Zanzibar is transitioning from a mid-tier coastal destination to a luxury and ultra-luxury market by statute and by demand, but on leasehold tenure with a 99 year ceiling and with disclosed climate exposure. The 2024 and 2025 arrivals data, the ZIPA Act 2018 framework, and the operator pipeline at Nungwi tell a consistent story: the conditions are forming, the constraints are real, and the underwriting requirements are explicit.
 Dossier
Marktanalysen
Branded Residences 2026: 910 Schemes, Two Markets
Savills counts 910 branded residence schemes at end-2025. Knight Frank counted 611 under a luxury-only screen in 2025 and 903 at end-2025 in its wider September 2026 survey, closing the 299-scheme gap this dossier read in May 2026 as the operational signature of a bifurcation. The bifurcation rests on operator and contract evidence rather than on the count. Tier 1 scarcity brands (Aman, Rosewood, Cheval Blanc, Bulgari) compound a 30 to 50 per cent premium. Tier 3 mass-luxury (Marriott Ritz-Carlton, St. Regis, JW, EDITION; Accor; Hilton Conrad) commodifies the premium toward 5 to 15 per cent in oversupplied markets. The Savills 33 per cent global average is a weighted composite of two distributions that move in opposite directions. This dossier reads the count as two markets, decomposes the premium into five components, and traces the holding-period asymmetry against the Vol.2 Lake Como unbranded heritage anchor. It is the third volume of Geography of Trust.