
Market Views
Where the World's Wealth Is Actually Moving in 2026
Henley's projection of 142,000 millionaire migrants in 2025 was challenged by Tax Policy Associates, which put one digit pattern in the underlying data at about a 1-in-240,000 chance and called the report marketing material, not evidence. For the UK, Henley's projected outflow of 16,500 has no official counterpart yet: HMRC counted 81,900 non-domiciled and deemed-domiciled taxpayers in 2024-25, and estimates of post-reform departures are due only in 2027. Beneficiaries of Italy's 24-bis regime reached 1,923 in 2024, 1,374 of them principal taxpayers, on Corte dei Conti figures. The Geography of Trust is now a three-vector portfolio decision, not a tax-haven shortlist.
 Illustration
Key takeaways
- - Henley's projection of 142,000 millionaire migrants in 2025 is contested: Tax Policy Associates put one digit pattern in the underlying data at about a 1-in-240,000 chance (27 July 2025), Henley announced an audit of New World Wealth in August 2025 without naming an auditor (Spear's), and its 2026 report of 16 June 2026 gives no migration count.
- - Henley projected a UK net outflow of 16,500 millionaires in 2025. HMRC counted 81,900 non-domiciled and deemed-domiciled taxpayers in 2024-25, the last year before abolition, and the government says accurate estimates of post-reform departures will only follow in 2027 (HMRC, 30 July 2026, reported by The National).
- - Italy's 24-bis charge rose from EUR 100,000 (2017) to EUR 200,000 (August 2024) and to EUR 300,000 for residence transfers from 1 January 2026 (idealista). Corte dei Conti figures put beneficiaries at 1,923 in 2024, 1,374 of them principal taxpayers (QuiFinanza, 26 June 2026).
- - Knight Frank's PIRI 100 for 2025: Tokyo +58.5%, Dubai +25.1%, Lake Como +6.5% (19th of 100). Knight Frank's forecast of about +3% for Dubai prime prices in 2026 was made in November 2025, before the Iran war.
- - BCG Global Wealth Report 2026: Hong Kong overtook Switzerland for the first time as the largest cross-border wealth hub, at about USD 2.9 trillion after 10.7% growth in 2025; BCG gives no Swiss figure (BCG Global Wealth Report 2026, 27 May 2026).
- - From 1 January 2026 DAC8 applies across the EU and 46 jurisdictions began collecting crypto-asset data under the OECD CARF, with 27 more committed for 2028 and 4 for 2029 (OECD, 14 September 2026). Victaura Research assumption: the 'privacy via opacity' model for crypto-assets closes once those cohorts exchange.
- - The Iran war that began on 28 February 2026 has reached the UAE: on 4 May 2026 Fujairah was struck in the first attack on the UAE since the 8 April ceasefire (Al Jazeera), and as of 26 September 2026 no ceasefire is in force (GlobalSecurity.org). Wynn expects a 'modest delay' to Al Marjan (Q1 2026 call, 7 May 2026).
On this page (30)
Revision notes
This article was corrected on 27 September 2026. A check of its figures and attributions against the cited sources found errors, which have been corrected in the text. The full list, with what the article said and what it says now, is in the corrections section at the end.
This article was corrected on 29 September 2026. An earlier version described Victaura's positions beyond its public project pages. The text, and the disclosure at the end, now follow those pages.
This article was corrected on 11 October 2026. An earlier version gave the Lake Como EDITION an opening date and a room count from a secondary report. They now follow the hotel's own opening announcement.
This article was corrected on 13 October 2026. It described the rise of Italy's Article 24-bis flat tax to €300,000 as still to come in 2026; it applies to those who transfer residence from 1 January 2026 (Law 199/2025, Normattiva), and the text now says so. The corrections and methodology sections said no source gives the 2024 taxpayer count; they now say the earlier version credited it to industry estimates. The text also said no published source estimates the charge's effect on new entrants; it no longer says so.
This article was corrected on 13 October 2026. The executive summary and section 4.4 dated Wynn Resorts' statement on the delay at Al Marjan to the day after its first-quarter earnings call. Both now give the day of the call, as the corrections section at the end already did.
This article was corrected on 13 October 2026. The methodology said that no published source breaks Italian Article 24-bis data down by country of origin. A 2026 Assonime study does so for a survey sample, and the methodology now cites it and says why a share of a sample is still not used as a proxy for departures from the United Kingdom.
This article was corrected on 13 October 2026. Sections 4.4 and 6.4 gave the Wynn Al Marjan budget without a date, and section 4.4 attributed the September 2027 opening to a CBRE review; they now give the budget announced in August 2026 and the date Wynn set with its second-quarter results.
Foreword
The figure of 142,000 millionaires moving countries in 2025 does not stand as evidence. The number, a Henley & Partners projection published on 24 June 2025 and recycled across the global trade press, was challenged in July 2025 by Dan Neidle of Tax Policy Associates, who found digit patterns in the underlying data that he put at about a 1-in-240,000 chance of occurring naturally, and concluded that the report should be treated as marketing material, not evidence. Henley announced an independent audit of its data partner New World Wealth in August 2025 (Spear's, 19 August 2025); no outcome has been published, and Henley's 2026 report, released on 16 June 2026, no longer gives a count of migrating millionaires. For the United Kingdom, Henley projected a net outflow of 16,500 millionaires in 2025. No official count of post-reform departures exists yet: HMRC counted 81,900 non-domiciled and deemed-domiciled taxpayers in 2024-25, the last year before abolition, down 1,200 on the year, and the government has said accurate estimates of departures since April 2025 will only follow in 2027 (HMRC release of 30 July 2026, reported by The National).
The migration is real. The headline counts drawn around it are not reliable.
Three concurrent shocks have reordered the geography of private wealth in the eighteen months to May 2026. The United Kingdom abolished a 226-year-old non-domiciled regime on 6 April 2025. On 1 January 2026 crypto-asset reporting began: DAC8 applies across the European Union, and 46 jurisdictions started collecting data under the OECD Crypto-Asset Reporting Framework (CARF) for first exchanges in 2027, with 31 more committed for 2028 or 2029 (OECD Global Forum, list updated 14 September 2026). The Iran war that began on 28 February 2026 reached the UAE within days: Fujairah was struck in March and again on 4 May 2026, the first attack on the UAE after the 8 April ceasefire (Al Jazeera, 4 May 2026). As of 26 September 2026 no ceasefire is in force: the truce collapsed on 8 July 2026 and the conflict remains unresolved (GlobalSecurity.org, 26 September 2026).
This dossier maps where wealth is actually moving in 2026, who is moving it, and which jurisdictions still clear the institutional bar once the marketing layer is stripped away. It is macro intelligence for principals and advisors. It is not investment advice.
| Published | 28 May 2026 |
| Edition | Volume 1, annual series |
| Author | Victaura Research / Greystone B.V. |
| Reading time | 35 minutes full read · 8 minutes executive summary only |
| Scope | Cross-border wealth, residence and prime real estate, 2025-2026 structural reordering |
| Disclosure | Victaura, through its parent Greystone B.V., develops projects on Lake Como, in Nungwi, Zanzibar, on Gili Air and in Uluwatu, Bali, and holds an off-plan capital position on Al Marjan Island, Ras Al Khaimah. See full disclosure §9 |
| Classification | Marketing material under MiFID II Article 24(3). Not investment advice. |
Five reasons to read this dossier
1. The Henley audit. Why the 142,000-migrants headline and the projected 16,500 UK outflow cannot be used as evidence, what HMRC's own non-dom statistics show so far, and why no reliable count of UK leavers to Italy or to Lake Como exists yet.
2. The booking-vs-residence-vs-operating distinction. What the BCG finding that Hong Kong overtook Switzerland as the largest cross-border booking centre (about USD 2.9tn, 27 May 2026) signals, and why the three geographies have decoupled.
3. The closing privacy window. How CARF and DAC8, with 46 jurisdictions collecting crypto-asset data from 1 January 2026 and 31 more committed for 2028 or 2029, extend automatic reporting to crypto-assets, and what compliance-by-design replaces the privacy-via-opacity model with.
4. The Italian flat-tax scaling. Why the 24-bis regime reached 1,923 beneficiaries in 2024 (1,374 principal taxpayers and 549 family members, on Corte dei Conti figures) as the annual charge for new entrants rose to EUR 300,000 from 2026, and where the binding constraint actually sits.
5. The Gulf re-rating. How the Iran war, with strikes on Fujairah from March 2026, reprices RAK and Dubai (residential sales value down nearly 20% in March 2026 on February, Wynn Al Marjan facing a 'modest delay'), and what the end of Gulf strategic hedging implies for a UAE-anchored platform.
Executive Summary
The findings below are presented as headline propositions. Each is developed, sourced and qualified in the body of the report.
1. The wealth migration is real, but its headline count is unreliable. Henley & Partners projected approximately 142,000 millionaire migrants globally in 2025. The figure is contested by Tax Policy Associates (Dan Neidle, July 2025), which found digit patterns in the underlying data with an estimated 1-in-240,000 chance of arising naturally. Henley announced an independent audit in August 2025; no outcome has been published, and its 2026 report of 16 June 2026 gives no migration count. For the United Kingdom, Henley projected a net outflow of 16,500 millionaires; HMRC's latest statistics show 81,900 non-domiciled and deemed-domiciled taxpayers in 2024-25, down 1,200 on the year, with estimates of departures since the April 2025 reform not due before 2027. The migration is happening. Its volume is not yet measured by any official source.
2. The UK to Italy corridor is one of three, not the corridor. Henley's 2025 report, itself contested, ranked the UAE (+9,800), the United States (+7,500), Italy (+3,600) and Switzerland (+3,000) as the largest net destinations globally, and named the UAE, Monaco, Malta, Italy, Greece, Portugal and Switzerland among the destinations of departing British millionaires, without a count per destination. Beneficiaries of Italy's Article 24-bis regime, family members included, rose from 1,136 in 2022 to about 1,495 in 2023 and 1,923 in 2024 (1,374 principal taxpayers and 549 family members), according to Corte dei Conti figures reported by Pagella Politica, MilanoFinanza and QuiFinanza.
3. The European tax-haven decade is closing by statute, not by accident. Within eighteen months: UK non-dom abolished April 2025; Portugal NHR closed 2023 and replaced with the narrower IFICI regime; Spain Golden Visa abolished by Ley Orgánica 1/2025 in April 2025; Malta citizenship-by-investment struck down by the Court of Justice of the European Union in C-181/23 on 29 April 2025. The new equilibrium runs through three replacement venues: Italy at €300,000 for those arriving from 2026, up from €200,000, the UAE Golden Visa, and the Swiss cantonal forfait.
4. Prime residential real estate has bifurcated. Knight Frank's PIRI 100 in The Wealth Report 2026, covering price changes in 2025, places Tokyo first at +58.5%, Dubai second at +25.1%, Lake Como at +6.5%, Milan at +0.4% and London at -4.7%. Knight Frank's forecast for Dubai prime prices in 2026, made in November 2025 before the Iran war, was about +3% (Khaleej Times, 24 November 2025).
5. The Geography of Trust framework rests on three vectors. We measure jurisdictions on Rule of Law, Climate Resilience and Social Cohesion. The Netherlands ranks tenth overall in the Fraser Institute's Economic Freedom of the World 2025, on 2023 data. Switzerland ranks third on ND-GAIN climate resilience. The UAE, at WJP rank 37 and Edelman Trust 80, exemplifies the divergence between experienced rule of law and surveyed institutional trust in autocratic information environments.
6. Booking centres, residence centres and operating centres are three distinct geographies, often confused. BCG Global Wealth Report 2026 records Hong Kong at about USD 2.9 trillion in cross-border booked wealth after 10.7% growth in 2025, overtaking Switzerland for the first time. Singapore had more than 2,000 tax-incentivised single family offices at end-2025, according to a written parliamentary reply by the MAS chairman. Yet Henley's contested 2025 projections put residence inflows highest in the UAE, the United States, Italy and Switzerland. Booking does not equal residence does not equal operating.
7. The geopolitical layer is no longer ambient. The Iran war began on 28 February 2026. Fujairah was struck in March and again on 4 May 2026, the first attack on the UAE after the 8 April ceasefire (Al Jazeera, 4 May 2026). As of 26 September 2026 no ceasefire is in force: the truce collapsed on 8 July 2026 and the conflict remains unresolved (GlobalSecurity.org, 26 September 2026). Wynn Resorts announced a "modest delay" to the Al Marjan Island opening on 7 May. The value of Dubai residential sales fell nearly 20% in March 2026 from February, to USD 10.1 billion (REIDIN data, reported by Business Upturn). Cinzia Bianco of the European Council on Foreign Relations has written that the war is a Zeitenwende for the Gulf (ECFR, 15 May 2026).
8. The generational transition is slow, not disruptive. Cerulli Associates projects USD 124 trillion transferred in the United States through 2048, an annual rate of approximately USD 5 trillion. Victaura Research assumption: NextGen preferences favour quiet luxury (Aman, Six Senses, Rosewood) over branded conspicuous consumption (Versace residences, Lamborghini towers). The transition is marginal in any given year, structural over a decade.
9. Transparency infrastructure is now permanent. Data collection under DAC8 across the EU and under CARF in 46 jurisdictions began on 1 January 2026, with 31 more jurisdictions committed to first exchanges in 2028 or 2029 (OECD Global Forum, 14 September 2026). Victaura Research reads this as closing the "privacy via opacity" model for crypto-assets by the end of the decade. Future residence and structuring decisions must be made on the assumption of full visibility.
Booking does not equal residence does not equal operating. The three geographies have decoupled.
The End of the Tax-Haven Decade
Eighteen months of statute have dismantled the European fiscal map of HNW residence. The dismantling is statutory, simultaneous across multiple jurisdictions, and irreversible in any near-term political horizon.
The United Kingdom. On 6 April 2025 the resident non-domiciled regime, in continuous operation since the Pitt income tax of 1799, was abolished and replaced by the four-year Foreign Income and Gains regime. HMRC's release of 30 July 2026 counts 81,900 non-domiciled and deemed-domiciled taxpayers in 2024-25, the last year before abolition, against 83,100 in 2023-24 (reported by The National, 31 July 2026). The Office for Budget Responsibility, in its supplementary costing of January 2025, estimated that the Conservative and Labour non-dom reforms together raise a net £33.9 billion from 2026-27 to 2029-30, after assuming that 25% of non-doms with excluded property trusts and 12% of other non-doms leave (as summarised by Tax Policy Associates). The forensic question is what the actual departure number has been.
The official evidence on departures is still thin. The Tax Justice Network, citing Financial Times reporting on HMRC data, said in August 2025 that the number of non-doms leaving the UK was in line with or below official forecasts (TJN, 14 August 2025). Dan Neidle of Tax Policy Associates argued in July 2025 that Henley's migration figures show statistical patterns inconsistent with measured data, including a digit clustering he put at about a 1-in-240,000 chance, and noted in June 2026 that Henley had dropped its data partner New World Wealth.
No official count of UK departures since April 2025 exists yet. HMRC's figure of about 9,000 individuals leaving the non-domiciled population in 2024-25 (11,200 the year before, with about 8,600 new arrivals) covers the year before abolition, and the government has said accurate estimates of departures since the reform will only be published in 2027 (The National, 31 July 2026). No published source counts how many UK leavers settled in Italy.
Spain, Portugal, Malta. Spain abolished its Golden Visa programme by Ley Orgánica 1/2025, effective 3 April 2025. Portugal closed the original Non-Habitual Resident regime in 2023 and replaced it with the IFICI regime, which is narrower in scope and limited to specific qualifying professions. Malta's citizenship-by-investment scheme was struck down by the Court of Justice of the European Union in case C-181/23 on 29 April 2025, closing the last EU passport-by-investment route.
Italy. The 24-bis regime, introduced in 2017 at a flat €100,000 substitute tax on foreign-source income, was doubled to €200,000 in August 2024 and rose to €300,000 for those transferring residence from 1 January 2026. Corte dei Conti figures, as reported in the Italian press, put beneficiaries (family members included) at 1,136 in 2022, about 1,495 in 2023 (1,070 principal taxpayers and 425 family members) and 1,923 in 2024 (1,374 principal taxpayers and 549 family members), with about EUR 469 million paid between 2020 and 2024, EUR 153 million of it in 2024 (Pagella Politica, 19 August 2024; MilanoFinanza, 22 October 2025; QuiFinanza, 26 June 2026). The Corte dei Conti, in its report on the state accounts published in June 2024, observed that the Agenzia delle Entrate knows neither the amount of foreign income subject to the substitute tax nor the ordinary tax that would have been due on it without the regime (as reported by Pagella Politica, 19 August 2024). The candour of that finding is a useful corrective to triumphalist readings of the regime's success.
The Corte dei Conti has acknowledged that granular data on foreign-source income under the substitute tax, and on the ordinary tax that would otherwise have been due, is not currently maintained by the Agenzia delle Entrate.
Paraphrase from Corte dei Conti, Relazione sul rendiconto generale dello Stato, June 2024 (as reported by Pagella Politica).
Greece, Switzerland, the Caribbean. Greece's Article 5A flat-tax regime, also at €100,000, had attracted 213 non-doms and investments worth over €277 million by June 2025, according to the Greek finance minister (VitalLaw, 30 June 2025). Switzerland's lump-sum forfait taxation regime is shrinking in numbers: 3,478 people were taxed on this basis in 2022, the latest national figure, against 4,557 in 2018 and 5,634 in 2012 (Blick, 24 August 2026; Swiss Federal Department of Finance for 2018). The canton of Ticino counted 725 globalisti at the end of 2024, paying CHF 189.5 million in cantonal, municipal and federal direct tax (Canton Ticino release, 26 September 2025). The Caribbean five (Antigua and Barbuda, Dominica, Grenada, Saint Kitts and Nevis, Saint Lucia) published a Memorandum of Agreement in March 2024 under which the minimum price of any citizenship-by-investment option is USD 200,000 from 1 July 2024 (OECS).
The political tone. Then French Prime Minister François Bayrou, in interviews on 1 September 2025, accused Italy of "fiscal dumping". Prime Minister Giorgia Meloni called the claims completely unfounded, and Foreign Minister Antonio Tajani said Italy does not practise fiscal dumping (Euronews, 1 September 2025). The exchange is illustrative of the closing-window dynamic: as remaining venues consolidate, intra-European political pressure on them will rise.
The Three Vectors of Trust
Where does capital go when it cannot be hidden? The Geography of Trust framework proposes that, in a post-CARF, post-DAC8 world, the binding constraints on residence and domicile decisions are no longer fiscal arbitrage but three institutional vectors: Rule of Law, Climate Resilience and Social Cohesion.
Vector One. Rule of Law
We triangulate three indices. The World Justice Project Rule of Law Index 2025 measures eight factors of experienced legal life, from constraints on government power to civil and criminal justice. The Fraser Institute Economic Freedom of the World 2025 measures market freedom on a libertarian frame, with its Legal System and Property Rights sub-index a particularly useful instrument for property-secure investors. The Heritage Foundation Index of Economic Freedom 2025 measures limitation of government from a conservative think-tank perspective.
A methodological caveat is essential. These three indices do not measure the same thing. WJP measures the lived experience of law, drawing on more than 215,000 household surveys and 4,100 expert surveys. Fraser measures the freedom of markets and the security of property, which correlates with but is not identical to rule of law. Heritage measures the size and reach of government, an explicitly normative metric. A jurisdiction that ranks high on Fraser and Heritage but low on WJP, or vice versa, is not internally inconsistent. It is a jurisdiction where the rule of law experienced by capital diverges from the rule of law experienced by citizens.
The WJP 2025 top ten reads: Denmark, Norway, Finland, Sweden, New Zealand, Germany, Luxembourg, Ireland, Netherlands (rank 9, score 0.82), Estonia. On the Fraser Institute's Economic Freedom of the World 2025, on 2023 data, the Netherlands ranks tenth overall. Singapore registers WJP rank 16 and ranks second overall on Fraser, a profile of high economic freedom with constrained civil liberties. The UAE registers WJP rank 37 and Edelman Trust 80, a divergence we treat in Vector Three.
The 2024 economics prize went to Daron Acemoglu, Simon Johnson and James Robinson "for studies of how institutions are formed and affect prosperity" (Royal Swedish Academy of Sciences, 14 October 2024). The Academy summarised their finding that societies with inclusive institutions grew wealthier while those with extractive institutions stayed poor. For the principal deciding where to domicile a multi-generational estate, this is the operative proposition.
Vector Two. Climate Resilience
The Notre Dame Global Adaptation Initiative (ND-GAIN) Country Index, in its most recent complete vintage, measures vulnerability and readiness on a composite frame. The leadership is Northern European and Pacific-rim: Norway ranks first, Finland second, Switzerland third. Denmark and Sweden follow, and Singapore ranks sixth, the only Asian country in the top ten (Climate Adaptation Platform, on ND-GAIN scores updated June 2025).
The financial signal is measurable. Swiss Re Institute reported USD 220 billion in economic losses from natural catastrophes in 2025, of which USD 107 billion were insured (Swiss Re Institute sigma, reported by Claims Journal, 24 March 2026). Bernstein, Gustafson and Lewis, in their 2019 Journal of Financial Economics paper, found that US coastal homes exposed to sea level rise sell for approximately 7% less than equivalent unexposed homes, a discount that has grown over time and is driven by sophisticated buyers and communities worried about global warming.
Copernicus C3S confirmed 2025 as the third-warmest year on record, at 1.47°C above the pre-industrial level, and 2023 to 2025 as the first three-year period to average more than 1.5°C above it (Copernicus C3S, Global Climate Highlights, 14 January 2026). James Hansen and colleagues estimated equilibrium climate sensitivity at 4.8°C ± 1.2°C for doubled CO2, above the IPCC AR6 likely range of 2.5 to 4°C (Hansen et al., Oxford Open Climate Change, 2023).
For a family comparing an estate in Lake Como (+6.5% in Knight Frank's PIRI 100 for 2025) with one in Dubai (+25.1%), the ND-GAIN sub-scores on water stress and heat exposure are a relevant input alongside price.
The 2023 to 2025 triennium was the first to average above 1.5°C versus pre-industrial baseline.
Paraphrase from Copernicus C3S, Global Climate Highlights, January 2026.
4.1 Reading the vectors together
The three vectors set out in Section 3, namely rule of law, climate resilience and social cohesion, do not produce a single ranking. They produce a topography. A jurisdiction can score in the top decile on legal infrastructure and still sit in the lower half on cohesion. Another can offer fiscal stability and physical safety while operating under a press regime that disqualifies it from any serious institutional disclosure. Reading the three vectors together, rather than collapsing them into a composite, is the analytical move that distinguishes a residence map from a marketing brochure.
What follows is a working tiering. It is not a league table. It groups jurisdictions by the structural quality of the platform they offer to a multi-jurisdictional family, and it flags, for each, the live friction that a credible advisor would surface in a first conversation.
4.2 Tier 1. Institutional bedrock
Three jurisdictions clear every vector at an institutional grade. The pre-eminence is consolidated, the frictions are known and bounded, and the advisory ecosystem is dense enough to absorb most edge cases.
Switzerland. ND-GAIN places Switzerland third globally on climate readiness. The cantonal forfait regime counted 3,478 taxpayers in 2022, down from 5,634 in 2012, while receipts held up: Ticino alone collected CHF 71 million more in 2024 than in 2016 (Blick, 24 August 2026). In the BCG Global Wealth Report 2026, Hong Kong overtook Switzerland for the first time as the largest cross-border wealth hub, at about USD 2.9 trillion after 10.7% growth in 2025; the BCG release gives no Swiss figure and attributes Hong Kong's rise to mainland China inflows, strong IPO activity and equity-market gains (BCG, 27 May 2026). The overtake matters as a directional signal, not as a reclassification. Tier 1 without qualification.
Netherlands. The Fraser Institute ranks the Netherlands tenth overall in Economic Freedom of the World 2025, on 2023 data. WJP places it ninth (0.82). Heritage's Index of Economic Freedom places it tenth. The institutional substrate is, on paper, among the strongest in the world. The candour required here is that the substrate is under live stress. The Schoof cabinet collapsed in June 2025 after the PVV left the coalition; after the October 2025 election, a D66-VVD-CDA minority cabinet led by Rob Jetten was due to be sworn in on 23 February 2026 (NL Times, 13 February 2026). The Netherlands was among twelve Member States that received letters of formal notice from the Commission on 30 January 2026 for not transposing DAC8 (KPMG, February 2026). The Dutch WJP score fell by less than 1% in 2025 (WJP, 28 October 2025). Article 120 of the Constitution still bars judicial review of primary legislation, a structural feature with cyclical consequences. Box 3 wealth tax remains unsettled. The actual-return bill passed the Lower House on 12 February 2026, but the Senate deferred its vote on 30 June 2026 pending an amending bill that, as of 27 September 2026, has not been submitted to parliament, so the planned 1 January 2028 start is not secured (Eerste Kamer, dossier 36.748). The Netherlands is the right operating jurisdiction for a regulated European platform and a credible EU passport vehicle. It is not, in 2026, a residence-tax-attractive jurisdiction in the way Switzerland or Italy are.
Singapore. WJP rank 16. Heritage rank 1. Global Peace Index 2025 rank 6 (score 1.357). More than 2,000 single family offices were receiving tax incentives at end-2025, according to a written parliamentary reply by MAS chairman Gan Kim Yong (Opalesque, 6 August 2026). Sections 13O and 13U remain the working tax frameworks for that population. AML supervision was tightened after the major money-laundering case of August 2023: on 4 July 2025 MAS imposed composition penalties totalling SGD 27.45 million on nine financial institutions for AML/CFT breaches linked to the case (MAS, 4 July 2025). Singapore is the rare jurisdiction that offers booking, residence and operating in a single coherent stack.
4.3 Tier 2. Established lifestyle, with caveats
These jurisdictions remain central to UHNWI portfolios for lifestyle, fiscal or strategic reasons. The friction in each case is identifiable and material.
Italy. WJP rank 34 of 143 in 2025, with Civil Justice at 53rd and 27th of 31 in its regional group of the EU, EFTA and North America (WJP, 28 October 2025). EIU Democracy Index 2024 score 7.58, classified a flawed democracy (EIU data compiled by Statranker). The constitutional referendum on the judicial reform failed on 22 and 23 March 2026, with 53.2 per cent voting against on a turnout of 55.7 per cent. V-Dem includes Italy in its 2026 list of ten autocratising countries (V-Dem, 17 March 2026). Victaura Research reads Italy as strong for fiscal residence and for lifestyle, and weaker for dispute resolution. On this reading, a family that chooses Italy for residence should not choose Italy for the seat of its contractual disputes.
United States. Global Peace Index 2025 rank 128 of 163 (Institute for Economics and Peace, reported by Time Out). WJP rank 27 in 2025. Steven Levitsky, Lucan Way and Daniel Ziblatt, in "The Price of American Authoritarianism" (Foreign Affairs, December 2025), examine the withering away of American democracy and the "competitive authoritarianism" taking its place (Harvard Department of Government, 16 December 2025). Eurasia Group named the "US political revolution" as the number-one risk for 2026 (Eurasia Group, Top Risks 2026, 5 January 2026). The US remains indispensable for capital markets access and for a class of operating businesses. It is no longer a passive choice for a residence platform.
United Kingdom. WJP rank 14 (0.78) in 2025 (WJP scores compiled by Statranker). Heritage rank 33. The non-dom regime was abolished in April 2025 and replaced by the four-year FIG regime; the government has said accurate estimates of departures since the reform will only follow in 2027 (The National, 31 July 2026). Knight Frank recorded prime central London prices down 3.3 per cent in the year to July 2026, the 39th consecutive month of annual declines (reported by Property Investor Today, August 2026). Super-prime sales above USD 10 million in Q4 2025 totalled 35 transactions, placing London seventh globally behind Sydney, Miami and Singapore (Knight Frank, February 2026). London remains a deep market and a legal centre of reference. It is no longer a tax-led destination.
Portugal. EIU Democracy Index 2024 score 8.08, classified a full democracy (EIU data compiled by Statranker). WJP rank 29 of 143 in 2025 (WJP, 28 October 2025). Heritage rank 25. The original NHR regime has been replaced by the IFICI regime, which is narrower in scope. Portugal remains a credible Iberian base for a defined cohort.
Greece. EIU Democracy Index 2024 score 8.07, classified a full democracy (EIU data compiled by Statranker). WJP rank 48 of 143 in 2025 (WJP, 28 October 2025). The Article 5A flat-tax regime for new tax residents, set at EUR 100,000 per year, had attracted 213 non-doms and investments worth over EUR 277 million by June 2025, according to the Greek finance minister (VitalLaw, 30 June 2025). The regime is small in numbers.
Saudi Arabia. EIU Democracy Index 2025 score 2.08, classified authoritarian at rank 147. The Premium Residency programme received 40,163 applications between January 2024 and July 2025, and 8,074 permits were issued in 2024, 5,578 of them (about 69 per cent) in the exceptional competence category, a profile weighted toward talent rather than investor capital (Gulf News). The Public Investment Fund suspended work on NEOM's The Line on 16 September 2025, and the fund has written down USD 8 billion across major projects including NEOM. The 2029 Asian Winter Games, awarded to Saudi Arabia in 2022, were moved to Almaty by the Olympic Council of Asia in February 2026 (Xinhua, 3 February 2026). Saudi Arabia is a strategic counterparty. It is not, in 2026, a residence platform for a Western family office.
4.4 Tier 3. Emerging, conditional
These jurisdictions are positioned for growth, narrative pull, or both. The conditionality is structural and should be priced.
United Arab Emirates. Edelman Trust Index 80 in 2026, which warrants the autocratic-trust caveat set out in Vector Three. RSF rank 158 of 180 in 2026, against 164 in 2025 (RSF). On 4 March 2025 an Emirati court upheld the convictions of 53 human rights defenders and political dissidents in a mass trial of at least 84 defendants (Human Rights Watch, 4 March 2025). The General Directorate of Residency and Foreigners Affairs in Dubai issued 158,000 golden visas in 2023, against 79,617 in 2022 (Gulf News). Knight Frank's PIRI index recorded Dubai prime residential prices up 25.1 per cent in 2025, placing Dubai second globally behind Tokyo at 58.5 per cent. Knight Frank's forecast for Dubai prime prices in 2026, made in November 2025 before the Iran war, was about 3 per cent, with its head of research for MENA pointing to a very real risk of supply outpacing demand (Khaleej Times, 24 November 2025).
The Iran war of 2026 has materially altered the risk picture. The war began on 28 February 2026. On 4 May 2026 an Iranian drone struck the Fujairah Petroleum Industries Zone, the first attack on the UAE since the 8 April ceasefire (Al Jazeera, 4 May 2026). As of 26 September 2026 no ceasefire is in force and shipping through the Strait of Hormuz remains partially disrupted (GlobalSecurity.org, 26 September 2026). Wynn Resorts said on 7 May 2026 that it expects a "modest delay" to Al Marjan (Skift, 8 May 2026). ECFR's Cinzia Bianco has written that the war is a Zeitenwende for the Gulf (ECFR, 15 May 2026). The value of Dubai residential sales fell nearly 20 per cent in March 2026 from February, to USD 10.1 billion (REIDIN data, reported by Business Upturn). The UAE remains a legitimate residence and operating choice. It is no longer a defensive one.
Ras Al Khaimah. CBRE expects more than 34,000 residential units to be delivered in RAK between 2026 and 2030, around 10,000 of them branded residences (CBRE Middle East, RAK H1 2026 review, reported by mid-east.info). Wynn Al Marjan was budgeted at USD 5.1 billion until August 2026 and at around USD 5.7 billion since (AGBI, 5 August 2026); its original target was Q1 2027, Wynn gave no new date when it announced the delay (Skift, 8 May 2026), and with its second-quarter results of 4 August 2026 it set the opening for September 2027 (Wynn Resorts, second quarter 2026 results release). Victaura Research assumption: the Macau expansion-and-correction cycle is a relevant base rate for an event-driven gaming market. RAK is a front-running trade.
Indonesia (Bali, Gili). WJP rank 69 (0.52) in 2025 (WJP scores compiled by Statranker). Foreign ownership is restricted to Hak Pakai, capped at 80 years, with no freehold route. Climate signal: De Clippele et al. (2023) projected that the Gili Matra marine protected area would cross the annual coral bleaching threshold by 2026.
Tanzania, Zanzibar. WJP rank 98 in 2025 (WJP scores compiled by Statranker). Under the Zanzibar Investment Act 2023, Strategic Investment Status requires USD 50 million on Unguja or USD 5 million on Pemba, with at least 30 per cent equity, or smaller amounts tied to job creation (Rive & Co). Foreign tenure is leasehold only; no freehold. This is a frontier market in the institutional sense. It is included here for completeness, not for default allocation.
4.5 Synthesis
The table below compares the jurisdictions by WJP rule of law rank, ND-GAIN climate rank where a verified rank exists, fiscal frame and direction in 2026.
| Tier | Jurisdiction | WJP RoL | ND-GAIN | Fiscal frame 2026 | Direction |
|---|---|---|---|---|---|
| Tier 1 | Switzerland | n/d (not ranked) | 3rd | Cantonal forfait, 3,478 taxpayers (2022) | Consolidating |
| Tier 1 | Netherlands | #9 (0.82) | n/d | Operating only; Box 3 reform on hold in the Senate | Stable, frictions live |
| Tier 1 | Singapore | #16 | 6th | Sections 13O/13U, 2,000+ SFOs | Consolidating |
| Tier 2 | Italy | #34 | n/d | 24-bis EUR 200k → EUR 300k 2026 | V-Dem autocratising list |
| Tier 2 | United Kingdom | #14 (0.78) | 8th | FIG four-year (from April 2025) | Repricing |
| Tier 2 | United States | #27 | n/d | SD/NV/DE trust situs | Levitsky competitive authoritarianism |
| Tier 2 | Portugal | #29 | n/d | IFICI (narrow scope) | Stable, narrower |
| Tier 2 | Greece | #48 | n/d | Art. 5A EUR 100k, 213 entrants (June 2025) | Small, stable |
| Tier 2 | Saudi Arabia | n/d | n/d | Premium Residency (talent 69%) | Strategic counterparty |
| Tier 3 | UAE | #37 | n/d | Golden Visa, 158k issued in Dubai in 2023 | Iran war exposure, repricing |
| Tier 3 | Ras Al Khaimah | (UAE) | (UAE) | Designated freehold zones | Event-driven, cycle risk |
| Tier 3 | Indonesia (Bali/Gili) | #69 (0.52) | n/d | Hak Pakai 80y, no Hak Milik | Constitutional scarcity |
| Tier 3 | Tanzania (Zanzibar) | #98 | n/d | Leasehold max 99y, ZIPA SIS | Frontier |
The map is no longer a ranking. It is a portfolio of platforms, each with a defined role and a defined limit.
5.1 The pattern
Victaura Research assumption: for UHNWI families with significant international exposure, the single primary residence is giving way to several habitual residences. In this reading the pattern in 2026 is three to four residences, distributed across the tiers described above and structured around a deliberate separation between booking centre, residence and operating jurisdiction. No survey cited in this dossier measures that number.
The survey evidence points to mobility at the level of the family office, not to a residence count. A figure of "4.2 properties on average", often attributed to Knight Frank, could not be traced to a Knight Frank publication and is not used here. KPMG and Agreus found that 44 per cent of family offices operated across more than one location in 2025, against 30 per cent in 2023 (2025 Global Family Office Compensation Benchmark Report, reported by InvestmentNews). The Capgemini World Wealth Report 2025, which surveyed 6,472 high-net-worth individuals including 5,473 next-generation HNWIs, found that 81 per cent of inheritors plan to switch wealth management firms within one to two years of inheritance (Capgemini, 2025).
5.2 The logic
The logic of the pattern is not lifestyle accumulation. It is risk distribution. Victaura Research assumption: a family with a Dubai operating base, a Lake Como secondary residence and a London or Zurich booking relationship is better placed to absorb a regional shock, of the kind delivered by the Iran war of 2026, than a family concentrated in one jurisdiction. No published source measures how families with and without a European fallback fared between February and May 2026.
The asset classes that work inside this logic are narrower than the brochure universe. Super-prime urban primary in jurisdictions with deep title and deep legal recourse. Branded residences, with the standing caveat that brand quality varies sharply. Alpine and lake assets, which Victaura Research reads as climate-resilient and legally robust; Lake Como rose 6.5 per cent in Knight Frank's PIRI 100 for 2025. Mediterranean lifestyle assets in jurisdictions where title is clean and where the fiscal frame is stable, which in practice narrows the working set to Italy, Greece, Portugal and, with conditions, Spain.
5.3 Booking, residence, operating
The single most important conceptual move is the separation of the three functions. They are routinely conflated in private-client conversations, and the conflation is the source of most structural error.
Booking is custody. In the BCG Global Wealth Report 2026, published 27 May 2026, Hong Kong overtook Switzerland for the first time as the largest cross-border wealth hub, at about USD 2.9 trillion after 10.7 per cent growth in 2025; the release gives no Swiss figure and attributes Hong Kong's rise to mainland China inflows, strong IPO activity and equity-market gains (BCG, 27 May 2026). The overtake is directionally important. Victaura Research reads it as driven largely by mainland-Chinese wealth booked in Hong Kong, a different population from internationally diversified UHNWI custody in the Swiss sense. BCG records UAE cross-border wealth rising 11.1 per cent in 2025, among the fastest-growing booking centres globally.
Residence is where the family lives, is taxed, and accesses healthcare and schooling. The credible residence shortlist for a Western UHNWI family in 2026 is shorter than the marketing universe suggests: Switzerland, Italy, Greece, Portugal, the United Kingdom under the FIG regime, Singapore, and the UAE with conditions.
Operating is where the regulated platform sits. Singapore offers the full triad, which is unusual. The Netherlands is a strong operating jurisdiction with a credible EU passport, and a weak residence jurisdiction. The DIFC and ADGM offer regulated operating platforms in the Gulf, with the regional caveats already noted.
5.4 The family office layer
The family office numbers warrant the same disambiguation discipline.
Singapore's figure is an official count of tax-incentivised structures. As of end-December 2025 more than 2,000 single family offices were receiving tax incentives in Singapore, according to a written parliamentary reply by Gan Kim Yong, Deputy Prime Minister and MAS chairman (Opalesque, 6 August 2026).
The DIFC figure is a wealth estimate, not regulated AUM. DIFC reports more than 1,250 family-related entities and says the top 120 families at the centre manage USD 1.2 trillion in assets globally (DIFC, November 2025). The two numbers measure different things and should not be summed or compared.
ADGM reported 11,128 active licences at the end of the first half of 2025 (ADGM). This is a licence count, not a family office count.
Politecnico di Milano's Osservatorio Family Office counted 244 family offices in Italy as of 1 June 2025, up 10.4 per cent on 2024. The total comprises 126 single family offices, 96 multi-family offices and 22 structures of banking origin (reported by WikiMilano), so it is not a count of single family offices alone.
KPMG and Agreus report that 44 per cent of family offices operated across more than one location in 2025, against 30 per cent in 2023 (2025 Global Family Office Compensation Benchmark Report, reported by InvestmentNews). That is a rise of 14 percentage points, or about 47 per cent, in two years, and Victaura Research reads it as consistent with the multi-jurisdictional thesis at the operating level.
5.5 The real-estate allocation, properly framed
The UBS Global Family Office Report 2025 puts real estate at 11 per cent of the 2024 global strategic asset allocation of the 317 family offices surveyed (UBS, reported by Caproasia).
The 11 per cent refers to the investment portfolio managed by the family office. Victaura Research assumption: it leaves out operating real estate held by the family business, habitual residences and real estate held through private equity vehicles, so real estate exposure on a total net worth basis is likely to be higher; no source cited here measures it. Advisors who quote 11 per cent as a total-wealth allocation are reading the figure beyond its perimeter.
5.6 The generational transfer, properly framed
Cerulli Associates projects USD 124 trillion in wealth transfers in the United States through 2048, more than half of it (USD 62 trillion) from high-net-worth and ultra-high-net-worth households, which make up about 2 per cent of households, and USD 18 trillion going to charity (Cerulli Associates).
The arithmetic deserves stating plainly. USD 124 trillion over roughly 25 years is about USD 5 trillion a year of flow. Victaura Research assumption: only a small fraction of that flow can reach prime real estate in any given year, so the transfer is structural and gradual rather than a single disruptive event, and frameworks that treat it as such will mis-price the timeline.
The 81 per cent figure from Capgemini refers to switching wealth managers, not to real estate or jurisdictional choice. The World Wealth Report 2025 finds that 81 per cent of inheritors plan to switch wealth management firms within one to two years of inheritance (Capgemini, 2025). Reading it as a statement about property or residence preferences overstates what the survey measured.
The next decade will test whether transparency norms hold under transfer pressure.
Victaura Research.
5.7 What this implies for the platform
The implication for a family considering its 2026 platform is not that it should hold four passports and four homes. It is that the platform should be designed against an explicit map of booking, residence and operating, against an explicit reading of the three vectors per jurisdiction, and against an explicit acceptance that the map will move. The Netherlands of 2026 is not the Netherlands of 2022. The UAE of May 2026 is not the UAE of January 2026. The platform should price the move, not assume the static.
Four geographies, four theses
The four markets discussed in this section are presented as case studies in how scarcity, regulation and capital flow interact at the geographic scale. They are not portfolio recommendations.
Disclosure: Victaura, through its parent Greystone B.V. (Netherlands), has an interest in each of the four markets below. It develops projects on Lake Como, in Nungwi, Zanzibar, and on Gili Air, as well as in Uluwatu, Bali, and holds an off-plan capital position on Al Marjan Island, Ras Al Khaimah. The analysis is offered with that interest declared; the data and source citations are independent.
The selection is deliberate. Two are mature European or established offshore markets (Lake Como, Ras Al Khaimah); two are frontier or boutique-scale (Zanzibar, Gili Air). The intent is not to argue all four are equivalently attractive. It is to show that "where trust travels" is not a single destination but a tiered map, with different regulatory grammars, different climate horizons and different buyer profiles per node.
| Market | PIRI / arrivals 2024-25 | Tenure | Statutory scarcity | Branded supply | Climate flag |
|---|---|---|---|---|---|
| Lake Como | PIRI +6.5% in 2025 (19th of 100) | Full freehold | D.Lgs. 42/2004 Art. 142 (300m band) | 3 residences planned (Corinthia, late 2028) | Alpine-lake, low |
| Zanzibar | 736,755 arrivals (+15.4%) | Leasehold max 99y | Land Tenure Act 1992 (leasehold only) | 70 apt (Anantara 2027) | SLR ~3.3 mm/y (East Africa, 1993-2023) |
| Gili Air | Bali 6.3M arrivals 2024 | Hak Pakai 80y (no Hak Milik) | Const. Art. 33(3) + UUPA 1960 | Boutique only | Annual bleaching projected from 2026 |
| Ras Al Khaimah | +118% transaction value 2024 | Freehold designated zones | None (cycle / absorption) | ~10,000 branded of 34,000+ units 2026-30 | Heat exposure |
6.1 Lake Como
Lake Como outperformed the global prime average in 2025. Knight Frank's PIRI 100 in The Wealth Report 2026 records Lake Como at +6.5% in 2025, 19th of 100 markets, against a global average of 3.2% and a European average of 3.3%; the report gives no five-year figure for Lake Como. Knight Frank notes that as prime supply tightened in Milan, buyers looked to Rome, Tuscany and the shores of Lake Como (The Wealth Report 2026). No 2025 figure for the share of foreign buyers on the lake could be traced to an Engel & Völkers or Nomisma publication, so none is given here.
Victaura Research assumption: the buyer base on the lake has changed in waves, from British visitors in the nineteenth century to German capital after the war and US private wealth in the 2000s. No source cited in this dossier dates these waves or measures a recent inflow of UK capital to Lake Como. The Wealth Report 2026 says the abolition of the UK non-dom regime triggered "meaningful, if undramatic" wealth outflows, with Italy, Monaco and Switzerland proving attractive among European markets, and that early signs point to incremental movement rather than a surge (Knight Frank, The Wealth Report 2026).
Italy's Article 24-bis regime, the flat-tax option for new tax residents, has become more expensive twice in under eighteen months. The annual substitute tax on foreign income was EUR 100,000 from 2017, rose to EUR 200,000 for new entrants in August 2024 and to EUR 300,000 for those who transfer tax residence from 1 January 2026, with the charge per family member rising from EUR 25,000 to EUR 50,000 (idealista, 15 December 2025). Corte dei Conti figures put beneficiaries at 1,923 in 2024, 1,374 principal taxpayers and 549 family members (QuiFinanza, 26 June 2026). No published source counts entrants of UK origin or says how many beneficiaries live on Lake Como, and the Agenzia delle Entrate publishes no geographic breakdown.
The supply constraint is more legible than the demand. Decreto Legislativo 42/2004, Article 142(1)(b), places under landscape protection by law the land within 300 metres of the shoreline of lakes; under Article 142(2) the protection does not apply to certain areas already urbanised on 6 September 1985, so it does not cover every metre of the Como shore. Works inside the band require landscape authorisation (autorizzazione paesaggistica). The band is the statute. Victaura Research assumption: in practice the authorisation makes new freestanding development very difficult, and substantial restoration of existing volumes is the operative path.
Branded residences on Como are notable for their absence. Among the new luxury schemes checked for this dossier, only Corinthia Lake Como at Menaggio includes a branded residential component: three residences in a 58-key resort targeting a late-2028 opening, subject to final planning approvals (Hospitality Net). The Lake Como EDITION at Cadenabbia, with 148 rooms, opened in preview in September 2025 ahead of its official opening in March 2026, the Ritz-Carlton Lake Como Bellagio is a 105-key conversion of the Hotel Grande Bretagne, and Six Senses Lake Como is a 102-room conversion of the Grand Hotel Cadenabbia; the published announcements of all three describe hotel rooms and no residences (EDITION Hotels, 12 November 2025; One Mile at a Time; TOP HOTEL NEWS, 25 October 2024).
The reading of this gap requires care. The intuitive narrative is that three global hotel brands have opened or announced hotels on Como without residences, so the opportunity is open. Victaura Research assumption: a more rigorous reading is that these operators, with full information, chose hotel-only for this market and that the choice has signal value; in this reading, established European buyers on Como prefer the autonomous villa to a visible brand, MENA and Asian NextGen buyers prefer other geographies, and the protected lakeshore complicates the branded model. No survey cited in this dossier measures these preferences.
The case for a successful branded scheme on Como therefore has to be argued site by site, with exceptional asset characteristics, an identified absorption pool, and ideally pre-launch letters of intent. The market-level gap is real. It is not, on its own, a thesis.
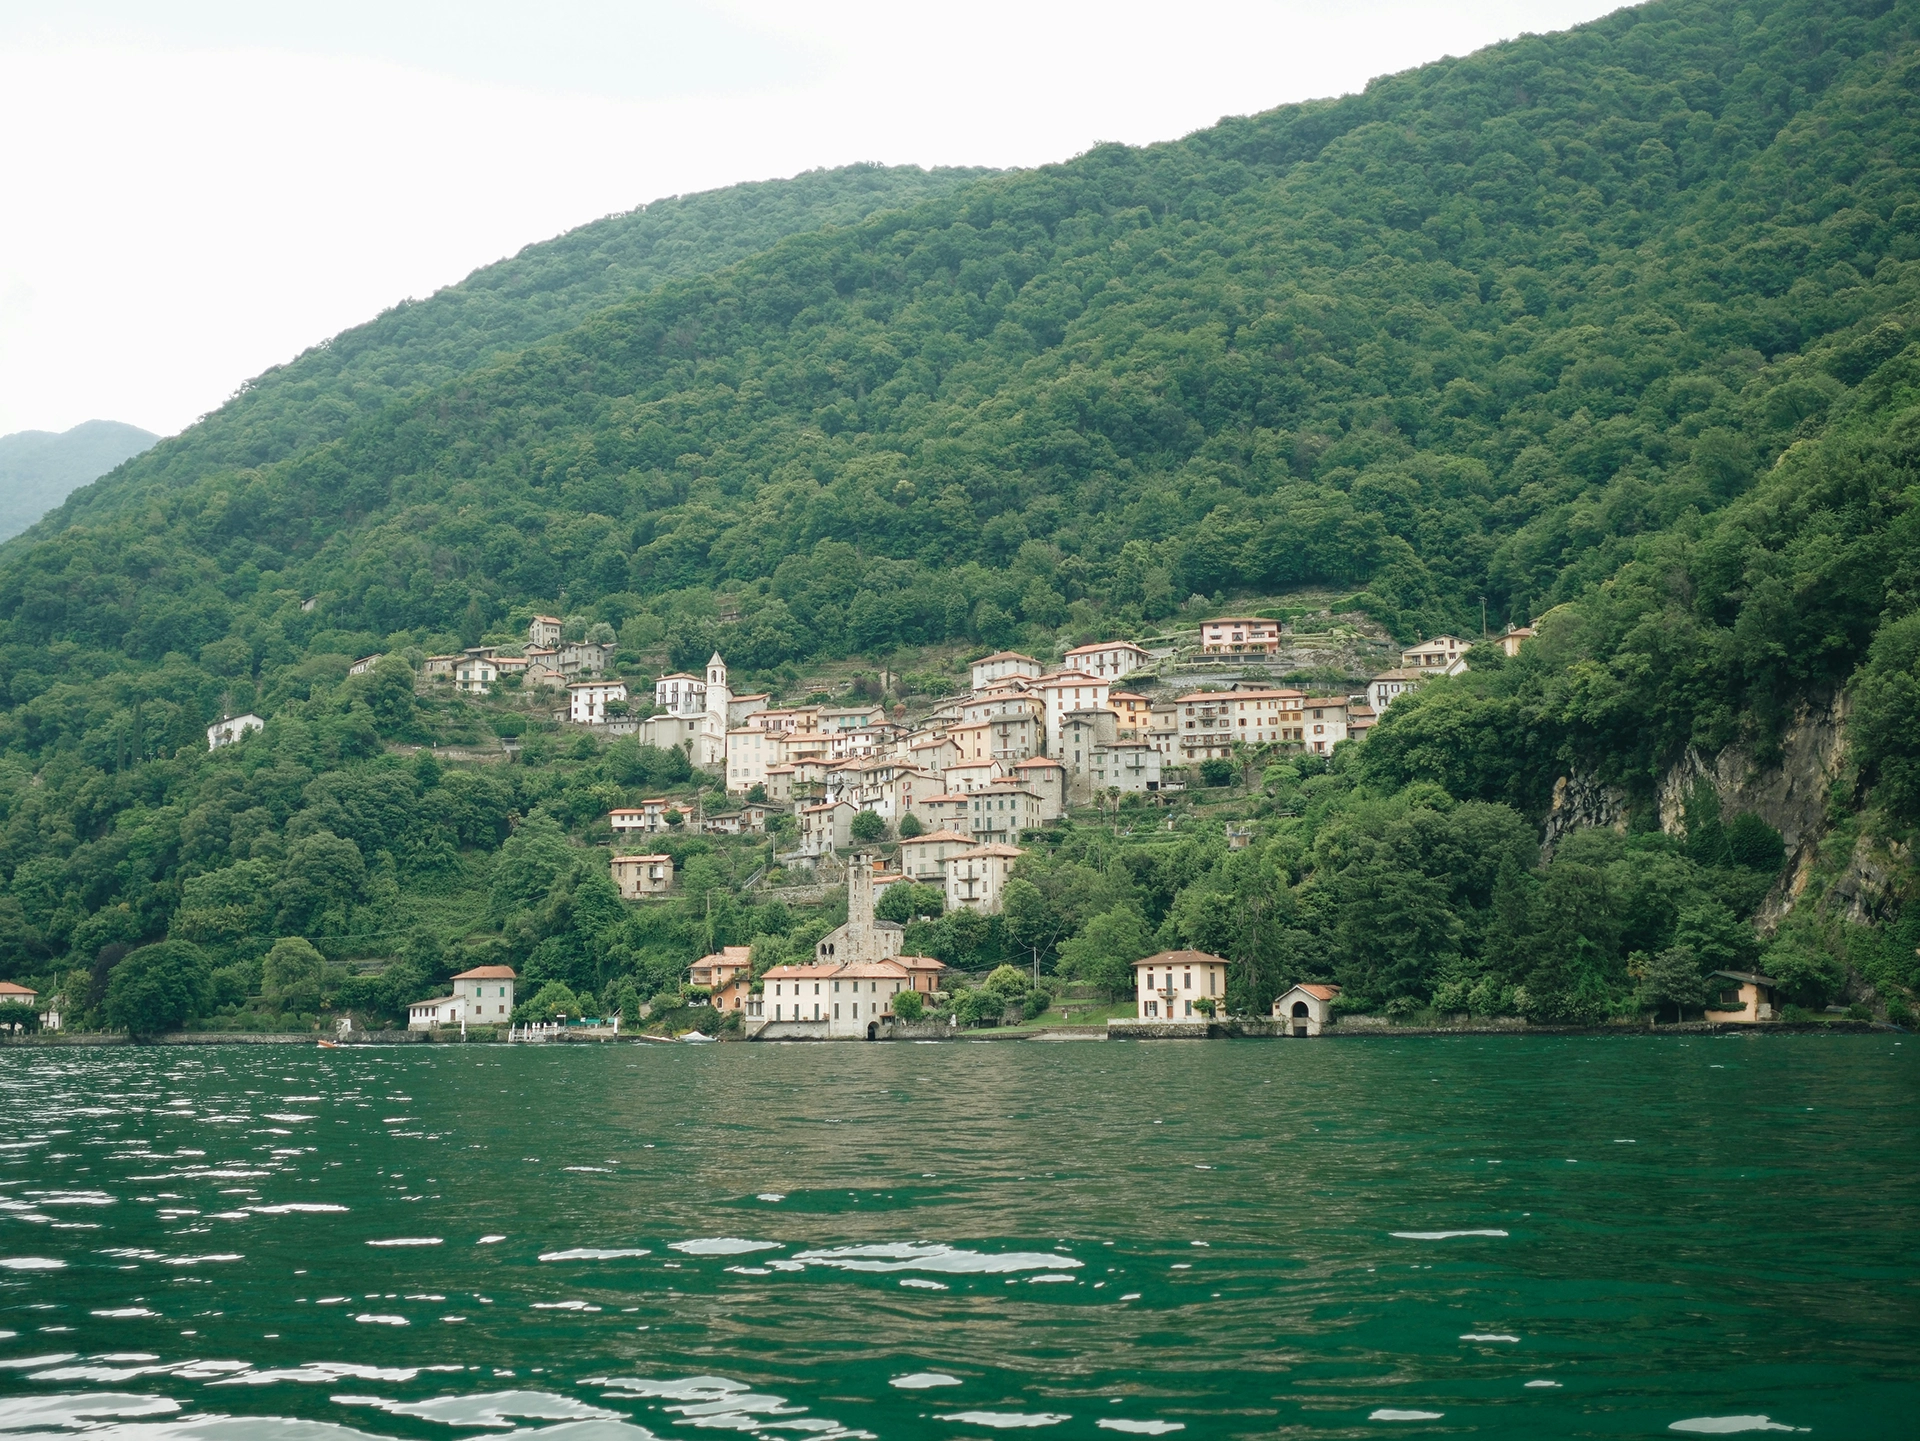
When sophisticated operators choose hotel-only for a market, the gap is a signal, not a vacuum. The thesis has to be argued site by site.
6.2 Zanzibar
Zanzibar received 736,755 international arrivals in 2024, an increase of 15.4% year on year (Office of the Chief Government Statistician, OCGS Zanzibar). European visitors comprise approximately 72% of arrivals, with Italy the single largest source market at 11.8%. This dependency on a narrow European corridor is itself a characteristic of the market that capital allocators should price.
The legal architecture is more constrained than is generally understood. All land in Zanzibar is public land: under the framework of the Land Tenure Act 1992, foreign investors cannot hold freehold and take leases of up to 99 years, renewable (Rive & Co). This is materially different from the freehold designated zones available in the United Arab Emirates and is closer in legal grammar to the Indonesian framework discussed below. The Zanzibar Investment Act 2023, which repealed the 2018 investment law (Charter Cities Institute, May 2024), grants Strategic Investment Status for USD 50 million on Unguja or USD 5 million on Pemba with at least 30 per cent equity, or smaller amounts tied to job creation, and provides that approved investments will not be seized except in the public interest and with fair and timely compensation (Rive & Co).
International hotel brands have arrived. Park Hyatt Zanzibar opened in Stone Town on 12 March 2015 as the first Hyatt hotel in Zanzibar (Hyatt). Anantara Zanzibar Resort & Residences, under development by Infinity Developments at Nungwi on the northern coast of the island, with a stated gross development value of approximately USD 150 million, comprises 111 hotel keys and 70 branded apartments and penthouses, with a 2027 opening target (project website).
The climate risk profile must be disclosed. Sea level in the Somali Coastal Current large marine ecosystem, along East Africa's Indian Ocean coast, rose by about 3.3 mm per year between 1993 and 2023, close to the global mean of 3.4 mm per year, and the rate across African waters accelerated to 4.34 mm per year in 2013 to 2023 (Kemgang Ghomsi et al., Communications Earth & Environment, 15 December 2025). Climate Watch Zanzibar identifies the east-coast beaches of Jambiani, Paje, Bwejuu and Michamvi as particularly exposed to erosion from high-energy waves and coral reef degradation. None of this invalidates the destination thesis. It does mean that asset selection at the parcel level, setback discipline, and a light operational footprint are not optional. They are underwriting requirements.
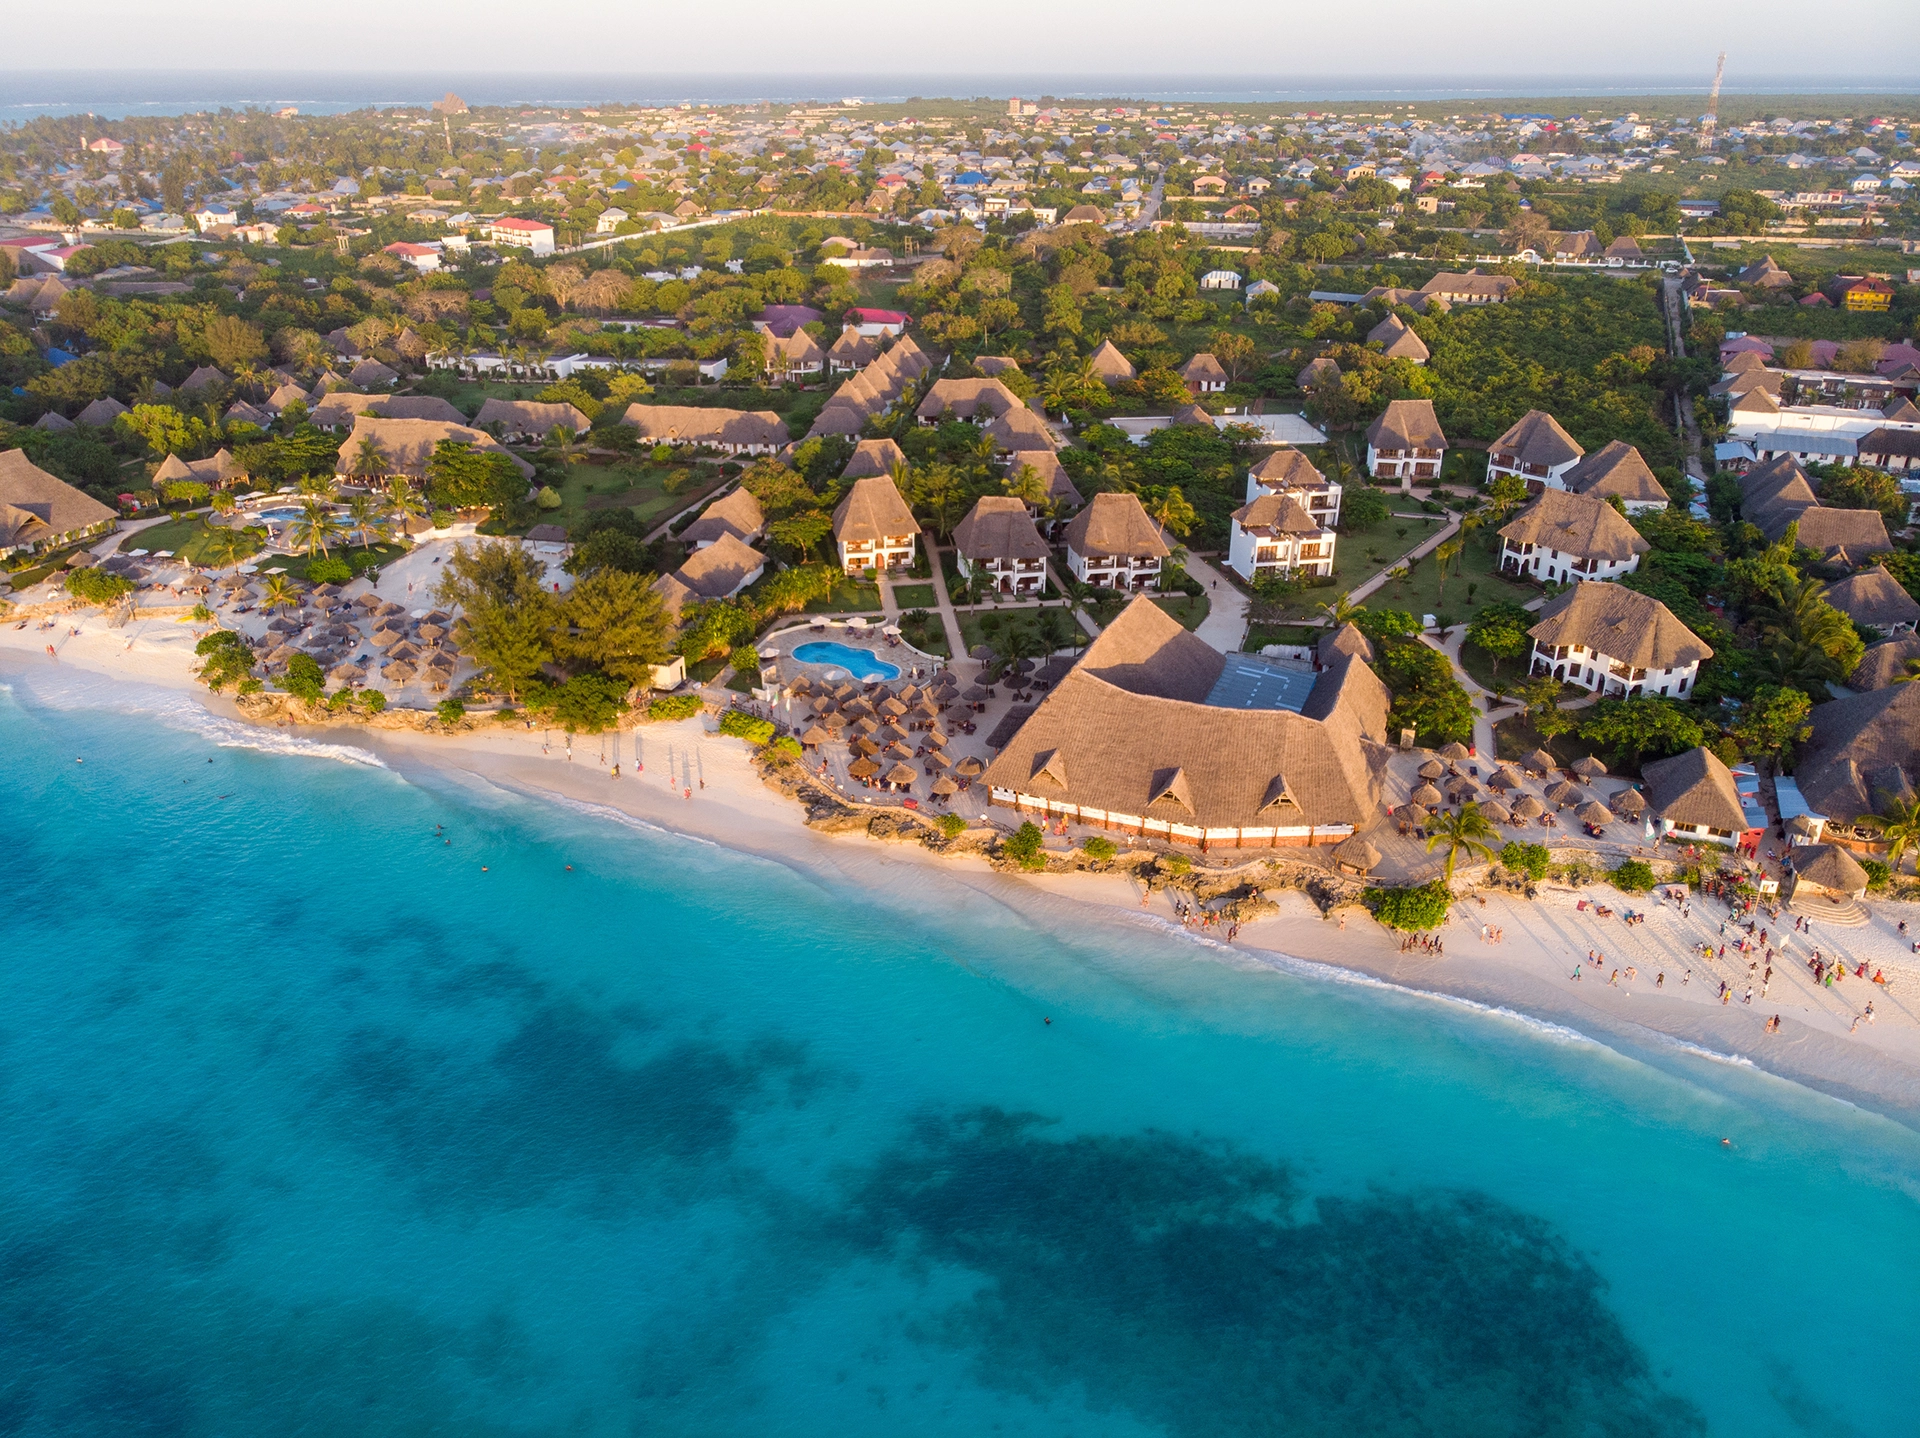
Foreign tenure in Zanzibar is leasehold, maximum ninety-nine years. There is no freehold. The statute is explicit. Underwriting that ignores this is not underwriting.
6.3 Gili Islands, Indonesia
Indonesia recorded 13.9 million international visitor arrivals in 2024, according to BPS-Statistics Indonesia (reported by Kontan), and Bali 6.3 million, according to the Bali Provincial Tourism Office (The Bali Sun, 3 January 2025). Victaura Research assumption: the Gili archipelago, off the northwest coast of Lombok, draws part of Bali's high-end overflow while its regulatory and physical footprint prevents Bali-style scale; no source cited here measures that share.
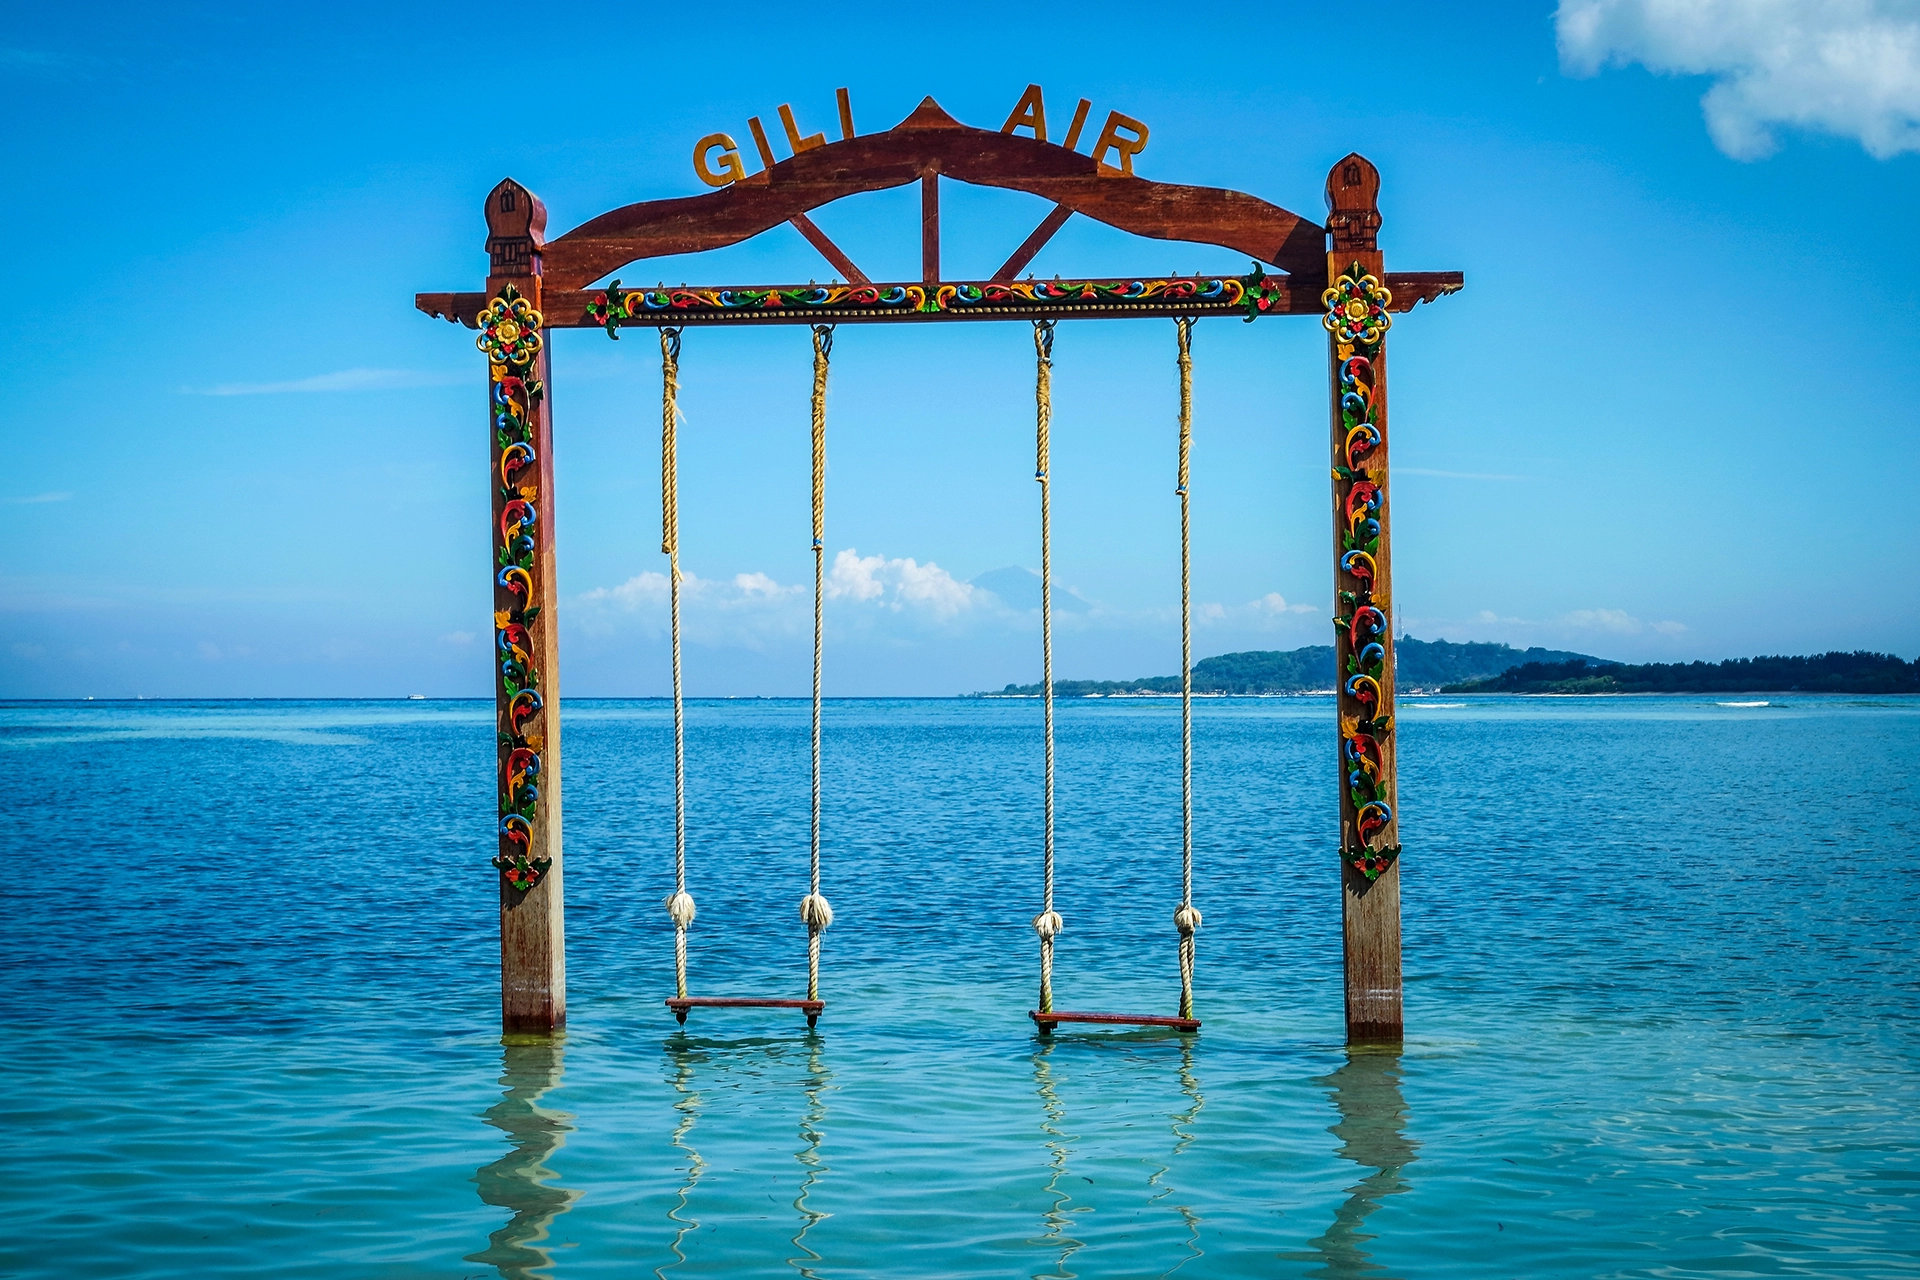
The foreign ownership framework is constitutional. Article 33(3) of the 1945 Constitution, together with the Basic Agrarian Law of 1960 (UUPA) Articles 9, 21 and 26(2), reserves Hak Milik (full freehold) for Indonesian citizens. Foreign buyers may hold Hak Pakai (Right to Use) for up to 80 years (30 + 20 + 30 under Government Regulation 18/2021), or take Hak Sewa (lease), or hold through a PT PMA foreign investment company that may take Hak Guna Bangunan (Right to Build) on land it does not own outright. This is constitutional scarcity layered on top of physical scarcity: Gili Air is a finite landmass on which freehold-equivalent supply is structurally capped.
Branded supply at scale is concentrated on Bali itself. Mandarin Oriental's resort on the Bukit peninsula includes 68 branded private villas, with opening scheduled for 2027 (Mandarin Oriental, 19 July 2024). On the Gilis, branded scale is not the operative model; boutique scale is. The combination of legal restriction, physical finitude and boutique appropriate scale is the thesis.
The climate caveat is comparable to Zanzibar. Research led by Laurence De Clippele of the University of Glasgow projects annual severe coral bleaching in the Gili Matra marine protected area from 2026 (The Conversation, 22 November 2023). The pattern in both Zanzibar and Gili Air is consistent: legally scarce, physically scarce, climate exposed. Asset selection and holding horizon are the underwriting variables.
6.4 Ras Al Khaimah
Ras Al Khaimah is the most legible case of an event-driven market re-rating in the current cycle. The catalyst is Wynn Al Marjan Island, an integrated resort that received the first commercial gaming facility licence in the United Arab Emirates from the General Commercial Gaming Regulatory Authority on 4 October 2024 (Wynn Resorts, 4 October 2024); its budget was USD 5.1 billion until August 2026 and has been around USD 5.7 billion since (AGBI, 5 August 2026). On the Q1 2026 earnings call of 7 May 2026, chief executive Craig Billings said the company expects a "modest delay" to the opening, citing logistical and shipping challenges in the region, and said Wynn was rerouting shipments and sourcing alternative materials where needed (call transcript, The Motley Fool; Skift, 8 May 2026). With its second-quarter results of 4 August 2026 Wynn set the opening for September 2027 (Wynn Resorts, second quarter 2026 results release).
The market response has been pronounced. The value of RAK real estate transactions rose 118 per cent in 2024, to AED 15.08 billion from AED 6.94 billion in 2023 (RAK Municipality data, reported by Kanebridge News, 14 February 2025). In H1 2026 apartment sale prices rose 18.0 per cent and villa prices 7.3 per cent year on year, and CBRE expects more than 34,000 residential units to be delivered between 2026 and 2030, around 10,000 of them branded residences (CBRE Middle East, RAK H1 2026 review, reported by mid-east.info).
The honest reading requires distinguishing two layers. The first layer is the gaming-driven re-rating itself. Victaura Research assumption: the Macau expansion-and-correction cycle is the relevant base rate for an event-driven gaming market, and underwriting that anchors to the upside case without scenario-weighting a Macau-style mean reversion is single-scenario underwriting. No source cited in this dossier publishes a consensus growth projection for RAK.

An event-driven market needs a correction scenario in the underwrite. A RAK underwrite built on the upside case alone is single-scenario underwriting.
The second layer is the geopolitical disclosure that the period 2026 to date requires. The US-Israel war on Iran began on 28 February 2026 and the Strait of Hormuz was largely closed from then on; on 4 May 2026 an Iranian attack hit the Fujairah Petroleum Industries Zone, the first attack on the UAE since the 8 April ceasefire (Al Jazeera, 4 May 2026). As of 26 September 2026 no ceasefire is in force and shipping through Hormuz remains partially disrupted (GlobalSecurity.org, 26 September 2026). Cinzia Bianco of the European Council on Foreign Relations writes that the UAE has "decided to retaliate to demonstrate its sovereign deterrence capabilities" and that the war is a Zeitenwende for the Gulf (ECFR, 15 May 2026).
The value of Dubai residential sales fell nearly 20 per cent in March 2026 from February, to USD 10.1 billion, the first significant monthly decline after a four-year post-pandemic boom, while average prices were reported only modestly lower, by around 4 to 5 per cent (REIDIN data, reported by Business Upturn). Victaura Research assumption: the standard argument that RAK and Dubai are independent allocations on a UAE map does not hold, because they are correlated on oil price, regional security, federal regulatory action and insurance and reinsurance pricing, so a "UAE diversification" within a single portfolio is a single exposure.
The foreign ownership framework, by contrast, is the most open of the four markets discussed. Ras Al Khaimah Law No. 11 of 2021 on the Real Estate Registry, an emirate law issued by the Ruler (Lexis Middle East), governs the property register, and foreign buyers can acquire freehold in designated areas such as Al Hamra Village, Mina Al Arab and Al Marjan Island (Will & Rich). The legal scarcity that is structural in Como, Zanzibar and Gili Air is, in RAK, the absence of constraint, not its presence. The scarcity argument has to be built on absorption, on cycle timing and on operator quality, not on tenure.
The successor lens
The intergenerational wealth transfer figure most often cited in allocator presentations, Cerulli Associates' USD 124 trillion through 2048 in the United States, is correct as published and often misread. The figure is the broad household-level transfer in the United States across the full wealth distribution. Cerulli attributes more than half of it, USD 62 trillion, to high-net-worth and ultra-high-net-worth households, about 2 per cent of households; the release gives no separate UHNW figure (Cerulli Associates). Divided across 25 years, the nominal annual flow is approximately USD 5 trillion at the household level. This is structural and gradual, not a disruptive single event. The UBS Billionaire Ambitions Report 2025 estimates that billionaires will transfer about USD 6.9 trillion globally by 2040, at least USD 5.9 trillion of it to children (UBS, 4 December 2025). Victaura Research assumption: that is the figure closest to the addressable population in the trophy property segment.
A second clarification is necessary. Regional sub-breakdowns of wealth transfer that circulate in industry decks without a traceable publication are not used anywhere in this dossier.
The structural friction in the Western transfer is the step-up in basis under United States tax law (26 U.S.C. § 1014). Boomer-owned trophy property carries embedded capital gains that, under current law, are eliminated at death through cost-basis step-up. This is a powerful incentive to hold property until inheritance rather than liquidate during life. Victaura Research assumption: for trophy property held by US taxpayers, in Aspen, the Hamptons, Palm Beach and Lake Tahoe and, where the owner is a US taxpayer, on Lake Como or the Côte d'Azur, the supply unlock is back-weighted toward the late 2030s and 2040s, not the late 2020s.
Asia is different. UBS estimates that about USD 11 trillion in private wealth will change hands across Asia-Pacific over the next 20 to 30 years (reported by the South China Morning Post, 12 May 2026). A report by the Bank of East Asia and Hurun Research puts the transfer by China's affluent households at about USD 3.09 trillion within a decade, USD 6.77 trillion in 20 years and USD 11.33 trillion in 30 years (Jing Daily, July 2026). Victaura Research assumption: the Asian transfer is denser, faster and more concentrated in first-generation founders handing to second-generation principals.
Knight Frank's NextGen survey in The Wealth Report 2025, covering 1,788 wealthy individuals aged 18 to 35, puts high-end real estate first among luxury assets (29.8%), ahead of luxury cars (27.8%) and private jets (15.1%). Among respondents with household income above USD 1 million, wellness and health is the top priority, at 24% (reported by Private Jet Card Comparisons, 6 March 2025).
The ESG signal from younger investors is weakening. A Stanford Graduate School of Business survey of US investors, conducted in autumn 2024, found that the share of young investors who considered it extremely important for investment companies to influence the environmental priorities of portfolio companies fell from 44 per cent in 2022 to 11 per cent (reported by phys.org, January 2025).
Victaura Research assumption: the NextGen branded-residence preference is differentiated, not monolithic. Among Western-educated, institutionally advised NextGen capital, the preference in this reading is for quiet luxury (Aman, Rosewood, Six Senses, Mandarin Oriental, low-key signalling) over loud luxury (Versace, Trump, fashion-house signage). Among MENA and certain Asian segments, loud-branded residences retain absorption. No survey cited in this dossier measures this split; the Knight Frank finding on wellness is consistent with it but does not test it.
The Western transfer is slow and back-weighted; the Asian transfer is faster and more concentrated. Allocation horizon should follow the geography.
Victaura Research.
The succession lens therefore reframes the supply question. In Victaura Research's reading, trophy property held by US taxpayers will not free up at scale before the late 2030s under current step-up rules, the Asian transfer is faster and more concentrated, and NextGen preference is differentiated, with high-end real estate first among luxury assets in the Knight Frank survey. Allocation horizon and geographic tiering matter more than aggregate-flow narratives.
Considerations for capital allocators
This section is descriptive rather than prescriptive. The considerations below are framed for family offices, principal investment advisors and private banks responsible for long-duration allocation. There is no product recommendation, and no direct or indirect call to action.
1. Scarcity is verifiable, not interpretive. The 300-metre Article 142 landscape band on Lake Como is 300 metres. Hak Milik in Indonesia is reserved for Indonesian citizens by Article 21 of the Basic Agrarian Law of 1960, a statute, not a policy. Zanzibar leasehold is statutory, not negotiable. Allocators can and should underwrite to the text of the regulation, not to the marketing summary of it.
2. Transparency infrastructure is closing the opacity model. DAC8 applies across the European Union from 1 January 2026, and under the Crypto-Asset Reporting Framework 46 jurisdictions began collecting data on that date for first exchanges in 2027, with 27 more committed for 2028 and 4 for 2029 (OECD Global Forum, list updated 14 September 2026). Victaura Research assumption: this materially compresses the privacy-via-opacity model for crypto-assets, and the compression will be largely complete once the 2028 and 2029 cohorts begin exchanging. Compliance-by-design is now the operative posture; opacity-by-design has a finite remaining horizon.
3. Geographic diversification must be tiered, not picked. The case studies in Section 6 are not interchangeable. They sit at different points on a regulatory, climate and cycle axis. Allocators are better served by a habitat-tiering exercise (mature Europe, established offshore, frontier coastal, event-driven Gulf) than by single-country selection.
4. Selection bias signals matter. When sophisticated luxury operators choose hotel-only for a given market, as the EDITION, Ritz-Carlton and Six Senses schemes on Lake Como did according to their published announcements, Victaura Research reads the absence of branded residences as a signal about that market, not a vacuum to be filled. A counter-thesis is legitimate but must be specific (site, buyer, pre-commitment), not analogical.
5. The Henley wealth migration dataset is directional only. It should be triangulated with HMRC statistics on non-domiciled taxpayers (the government has said accurate estimates of departures since April 2025 will only be published in 2027; The National, 31 July 2026), BCG Global Wealth Report cross-border booked wealth figures and Capgemini HNWI population stocks. The independent audit of New World Wealth's methodology that Henley announced in August 2025 named no auditor (Spear's, 19 August 2025), and Henley's 2026 report, released on 16 June 2026 with AlphaGeo as analytical partner, gives no count of migrating millionaires (Henley & Partners, 16 June 2026). Citations should reflect that status.
6. Generational handoff is asymmetric. Victaura Research assumption: the Western transfer is slow (step-up in basis, longevity, an unlock back-weighted to the late 2030s and 2040s), while the Asian transfer is faster and more concentrated. UBS estimates that about USD 11 trillion in private wealth will change hands across Asia-Pacific over the next 20 to 30 years (reported by the South China Morning Post, 12 May 2026). Allocation horizon should match the geography, not the aggregate global figure.
7. Climate physical risk is already priced into coastal property. Bernstein, Gustafson and Lewis (Journal of Financial Economics, 2019) found that US homes exposed to sea level rise sell for approximately 7% less than equivalent unexposed properties, a discount that has grown over time and is driven by sophisticated buyers. For a 30 to 50 year holding horizon, parcel-level climate diligence is not an externality. It is an underwriting input.
Methodology and sources
All figures in this dossier are attributed in line to a named source. Where the source is secondary, such as a press report of official data or a compilation like Statranker, it is named as such, and Victaura Research assumptions are labelled as assumptions.
Henley & Partners citizenship migration dataset. Used as a directional indicator only. The statistical critique by Dan Neidle (Tax Policy Associates, 27 July 2025), the absence of a named auditor for the review of New World Wealth's methodology announced in August 2025 (Spear's, 19 August 2025) and the absence of any migration count in Henley's 2026 report of 16 June 2026 limit the dataset's standing as a primary source.
Boston Consulting Group Global Wealth Report. All BCG GWR figures cited refer to the 2026 edition, published 27 May 2026.
HMRC United Kingdom non-domicile data. The UK figures in this dossier come from HMRC's statistics on non-domiciled taxpayers released on 30 July 2026, covering 2024-25, the last year before abolition (reported by The National, 31 July 2026). The government has said accurate estimates of departures since April 2025 will only be published in 2027. Italian 24-bis data are not used as a proxy for UK departures. The one breakdown by country of origin found comes from a survey. Among about 1,300 beneficiaries reported by twelve law and tax firms, nearly 40% had last been tax resident in the United Kingdom (Assonime, Towards Italy, No. 7/2026), which is a share of a sample and not a count of departures.
Italian 24-bis figures. The 2024 figures used are those of the Corte dei Conti, as reported in the Italian press: 1,923 beneficiaries, of whom 1,374 principal taxpayers and 549 family members, with about EUR 469 million paid between 2020 and 2024, EUR 153 million of it in 2024 (QuiFinanza, 26 June 2026). An earlier series running from 94 taxpayers in 2017 to about 1,631 in 2024, whose last figure the earlier version credited to industry estimates, is not used. No geographic breakdown of beneficiaries by the Agenzia delle Entrate could be found.
Edelman Trust Barometer. Cited where used, with disclosure of the Clean Creatives critique and the Tannenberg autocratic-trust bias discussion.
Quotes and attribution. Verbatim quotation is limited to published text that could be checked: Cinzia Bianco (ECFR, 15 May 2026), Craig Billings of Wynn Resorts on the Q1 2026 earnings call of 7 May 2026 (transcript, The Motley Fool), the Royal Swedish Academy of Sciences' 2024 prize citation and The Wealth Report 2026. The Corte dei Conti finding on missing data, from the report published in June 2024, is given as a paraphrase. Paraphrases attributed to Helen Miller (IFS), Mark Bou Mansour (TJN), Liam Bailey (Knight Frank) and Rebecca Gooch (Deloitte Private) could not be traced to a source and have been removed.
Forward references. This is Volume 1 of an intended annual series. Volume 2 (2027) will incorporate the HMRC post-reform UK series, the Henley independent review outcome (if published with named auditor), and the first full post-CARF / DAC8 reporting cycle. Methodology refinements will be documented in the edition rather than retroactively.
Skin in the game disclosure. Victaura, through its parent Greystone B.V. (Netherlands), develops projects on Lake Como (Italy), in Nungwi, Zanzibar (Tanzania), on Gili Air and in Uluwatu, Bali (Indonesia), and holds an off-plan capital position on Al Marjan Island, Ras Al Khaimah (UAE). Readers should assume commentary may be influenced by, or benefit, these positions. This document is classified as marketing material under MiFID II Article 24(3). It is not investment advice.
Corrections, 27 September 2026
This dossier, published on 28 May 2026, said the Dutch Box 3 wealth tax would remain unsettled until a 2028 reform window, and as of 27 September 2026 even the 2028 start is not secured. The 2028 date was the government's plan at the time of publication. The actual-return bill (Wet werkelijk rendement box 3, dossier 36.748) passed the Lower House on 12 February 2026. On 30 June 2026 the Senate (Eerste Kamer) agreed to defer its vote until an announced amending bill, a novelle, has been debated (Eerste Kamer, plenary record of 30 June 2026). On 14 September 2026 the Minister and State Secretary of Finance told the Senate that an amendment with broad parliamentary support was not yet possible and asked it to keep the bill on hold (Kamerstuk 36.748, Q). Mercurius Vermogensbeheer, a Dutch wealth manager, places the next decision at the 2027 Spring Memorandum (19 September 2026, secondary source). The corrected passages are the Netherlands entry in Section 4.2 and the synthesis table. The reading of the Netherlands is unchanged, a strong operating jurisdiction and a weak residence-tax one.
A further review on the same day refined some of the corrections above and fixed further points. The article said Henley's 142,000 figure 'fails forensic peer review at the 1-in-240,000 anomaly threshold'; it now says that Tax Policy Associates put one digit pattern in the underlying data at about a 1-in-240,000 chance, a statistical critique rather than a peer review (Tax Policy Associates, 27 July 2025). It said an independent review was requested in September 2025; Henley announced the audit in August 2025 (Spear's, 19 August 2025), and the article now adds that Henley's 2026 report of 16 June 2026 gives no migration count. It gave an effective UK outflow of 1,800 to 3,800 from CenTax and Companies House data, with 400 to 600 movers to Italy; no source contains these figures, so they have been removed, and the article now cites HMRC's count of 81,900 non-domiciled and deemed-domiciled taxpayers in 2024-25 and states that no post-reform departure count exists yet (HMRC, 30 July 2026, reported by The National). This removes a pillar of the original thesis: the article can say the Henley count is unreliable, not that the real UK outflow is an order of magnitude smaller. It said CARF and DAC8 went live across 76 jurisdictions on 1 January 2026; the OECD list shows 46 jurisdictions collecting data from that date and 31 more committed for 2028 or 2029 (OECD Global Forum, 14 September 2026). It said Italy's 24-bis regime grew 17-fold from 94 taxpayers in 2017 to about 1,631 active taxpayers in 2024; Corte dei Conti figures give 1,923 beneficiaries in 2024, 1,374 of them principal taxpayers, and the 2017 to 2020 series and the 17-fold multiple could not be verified and have been removed (QuiFinanza, 26 June 2026). It dated the Corte dei Conti finding on missing data to a 2025 report; it comes from the report published in June 2024 (Pagella Politica, 19 August 2024). It gave London prime prices at -2.2%; Knight Frank's PIRI 100 records -4.7% for 2025 (The Wealth Report 2026). It gave Hong Kong and Switzerland at USD 2.95 and 2.94 trillion; the BCG release gives about USD 2.9 trillion for Hong Kong and no Swiss figure (BCG, 27 May 2026). It said the Netherlands ranks first on the Fraser legal-system sub-index at 8.93; this could not be verified and the article now says the Netherlands ranks tenth overall in Economic Freedom of the World 2025. It said Dubai transactions fell 20% year on year in March 2026; the value of residential sales fell nearly 20% from February (REIDIN, reported by Business Upturn). It quoted Cinzia Bianco calling the UAE a 'front-line state'; the ECFR article cited does not contain the phrase, and the article now reports her view that the war is a Zeitenwende for the Gulf (ECFR, 15 May 2026). It said Fujairah was struck in early May 2026; it was struck from March and again on 4 May (Al Jazeera, 4 May 2026), and the article now states that as of 26 September 2026 no ceasefire is in force (GlobalSecurity.org). It attributed a £33.9 billion yield to an OBR note of April 2026; the figure comes from the OBR's January 2025 costing and covers 2026-27 to 2029-30 (Tax Policy Associates). Paraphrases attributed to Helen Miller and Mark Bou Mansour without a traceable source have been removed.
A third review on the same day corrected further points. The review of Sections 3 and 4 found figures that the earlier corrections had not reached. A statistic still showed 17-fold growth in Italy's 24-bis regime, and two passages still gave the Netherlands a Fraser legal-system score of 8.93, although the corrections list said both had been removed; they are now gone, and the Netherlands is given its verified rank of tenth overall in Economic Freedom of the World 2025. The article said the Swiss lump-sum regime was stable at about 4,700 taxpayers in 2024; the latest national figure is 3,478 in 2022, down from 4,557 in 2018 and 5,634 in 2012 (Blick, 24 August 2026). It dated Greece's 213 non-dom entrants and EUR 277 million to end-2024; the finance minister gave these figures in June 2025 (VitalLaw, 30 June 2025). It described Ticino's CHF 189.5 million as cantonal receipts; the figure includes municipal and federal direct tax (Canton Ticino, 26 September 2025). It said the Caribbean price floor was forced by EU and US pressure and that Italy's finance ministry answered François Bayrou; neither claim is in the sources, and the answer came from Giorgia Meloni and Antonio Tajani (Euronews, 1 September 2025). Two passages still gave Swiss and Hong Kong booked wealth as USD 2.94 and 2.95 trillion; BCG gives about USD 2.9 trillion for Hong Kong and no Swiss figure (BCG, 27 May 2026). It gave Edelman 2026 trust scores of 78 for Saudi Arabia and 76 for India; they are 73 and 74 (Edelman, January 2026). It gave the UAE's press freedom rank as 164 of 180; that was 2025, and the 2026 rank is 158 (RSF). It described an HRW report on a mass trial of 84 defendants; the March 2025 ruling upheld the convictions of 53 of at least 84 people charged (Human Rights Watch, 4 March 2025). It said survey trust in autocracies is overstated by a factor of 1.3 to 1.8 and that Clean Creatives documents Edelman work for state-owned enterprises; neither is in the sources. It gave ND-GAIN ranks for Singapore (fifth), the Netherlands, Italy, the UAE, Indonesia and Tanzania; Singapore is sixth, and the other ranks could not be verified and have been removed from the text. It said 2025 was the sixth consecutive year of economic catastrophe losses above USD 100 billion; Swiss Re reports USD 220 billion of economic losses, of which USD 107 billion were insured, and the six-year run refers to insured losses. It said the Bernstein, Gustafson and Lewis discount applied to Florida homes and a filtered buyer pool; the paper finds about 7% on US coastal homes, driven by sophisticated buyers. It said James Hansen places climate sensitivity at the upper end of the IPCC range; his 2023 estimate of 4.8°C is above the IPCC likely range. It dated V-Dem's 91 autocracies against 88 democracies to the first time since 2002; V-Dem says the first time in over 20 years. It gave academic and media freedom as the basis for listing Italy as autocratising; V-Dem's release names Italy without that detail. It said the MAS chairman reported more than 2,000 enforcement actions under the Securities and Futures Act in 2024; no source supports this, and the article now cites SGD 27.45 million in penalties on nine institutions (MAS, 4 July 2025). It also now states that a new Dutch cabinet took office in February 2026 (NL Times, 13 February 2026), and it replaces a paraphrase of an Acemoglu Nobel address with the Academy's prize citation.
A fourth review on the same day corrected further points. It covered Sections 4.3 to 5.6. The article gave Portugal and Greece WJP ranks of 28 and 47; they are 29 and 48 (WJP, 28 October 2025). It gave Italy an EIU rank of 37 and a civil enforcement score of 0.36, the lowest in the G7; neither could be verified, and the article now gives Italy's EIU 2024 score of 7.58 and its WJP Civil Justice rank of 53. It said the judicial referendum failed with 53.7 per cent against; the result was 53.2 per cent. It gave a BTP-Bund spread move of 45 to 50 basis points and coalition polling of 42 per cent; no source contains them and they have been removed. It said Eurasia Group ranked the US political revolution as the top risk for 2025; it was the top risk for 2026 (Eurasia Group, 5 January 2026). A remark attributed to Larry Diamond could not be traced and has been removed. It gave prime central London prices down 2.2 per cent in May 2026; the latest Knight Frank figure is minus 3.3 per cent in the year to July 2026 (Property Investor Today, August 2026). It gave V-Dem ranks for Portugal and Greece and a 'Henley scoring' of 5A for Greece; the article now gives their EIU 2024 full-democracy scores of 8.08 and 8.07. It called Greece's EUR 277 million cumulative receipts; the finance minister described it as investments (VitalLaw, 30 June 2025). It said NEOM's population target had been cut by 99 per cent, which no source contains, and that the USD 8 billion write-down was on NEOM alone; it covers major projects including NEOM. It gave the UAE's press freedom rank as 164; the 2026 rank is 158 (RSF). It said Human Rights Watch documented 53 people sentenced; the court upheld the convictions of 53 of at least 84 defendants (Human Rights Watch, 4 March 2025). It gave 158,000 cumulative UAE golden visas to end-2024 from the Ministry of Economy; the figure is 158,000 issued in Dubai in 2023 by the Dubai residency authority (Gulf News). It said Knight Frank noted the Dubai market may have peaked; the source warns of supply outpacing demand (Khaleej Times, 24 November 2025). It said Hormuz was closed and Dubai prices fell 20 per cent year on year, and quoted Cinzia Bianco calling the UAE a 'front-line state'; the article now reports the 4 May Fujairah strike as the first since the 8 April ceasefire (Al Jazeera, 4 May 2026), states that as of 26 September 2026 no ceasefire is in force and Hormuz shipping remains partially disrupted (GlobalSecurity.org), gives the nearly 20 per cent fall in the value of March sales from February (REIDIN, reported by Business Upturn) and cites Bianco's view that the war is a Zeitenwende for the Gulf (ECFR, 15 May 2026). It said CBRE tracks about 9,000 branded units in RAK, that the Mondrian launch sold out within hours and that Wynn Al Marjan was pushed to Q1 2027; CBRE expects around 10,000 branded units among more than 34,000 by 2030, the Mondrian claim has been removed, and Q1 2027 was the original target, with CBRE now expecting September 2027 (CBRE H1 2026 review). The Macau base rate is now labelled a Victaura Research assumption. It said monitoring confirmed annual coral bleaching at Gili Matra since 2026; De Clippele et al. projected it. In the synthesis table, Switzerland's WJP 'top 10' has been removed because Switzerland does not appear in the 2025 WJP ranking, the Swiss lump-sum count of about 4,700 is now 3,478 for 2022 (Blick), Singapore's ND-GAIN rank is sixth, the United Kingdom's is eighth, and unverified ND-GAIN ranks for five countries have been removed. It said Capgemini found 81 per cent of NextGen work remotely; the figure refers to inheritors planning to switch wealth managers (Capgemini, 2025). The three-to-four residence pattern and the claim that families without a European fallback stopped functioning in 2026 are now labelled Victaura Research assumptions. It attributed the Singapore count of 2,000 family offices to MAS testimony; it comes from a written parliamentary reply on tax-incentivised offices (Opalesque, 6 August 2026). It gave DIFC 671 foundations; DIFC reports more than 1,250 family-related entities (DIFC, November 2025). It gave Hong Kong and Switzerland at USD 2.95 and 2.94 trillion and UAE booked wealth at USD 721 billion; BCG gives about USD 2.9 trillion for Hong Kong, no Swiss figure and 11.1 per cent growth for the UAE (BCG, 27 May 2026). It said UBS, Goldman Sachs and Campden converge on a median real estate allocation of 11 per cent and put total-wealth exposure at 25 to 40 per cent; UBS reports 11 per cent, and the other sources and the range could not be verified. It described Cerulli's USD 124 trillion as North American; it is a US figure. Paraphrases attributed to Rebecca Gooch, Mark Bou Mansour and Helen Miller in Section 5.6 had no traceable source and have now been removed from that section.
A fifth review on the same day corrected further points. A review of the passages from the pullquote in Section 5.6 to the Zanzibar case study corrected further points. A pullquote was attributed to Mark Bou Mansour of the Tax Justice Network without a traceable source; it is now attributed to Victaura Research. The article said Lake Como was the strongest European prime lake market and had risen 54 per cent over five years in Knight Frank's index; The Wealth Report 2026 records +6.5 per cent in 2025, 19th of 100 markets, against a global average of 3.2 per cent, and gives no five-year figure for Lake Como. It attributed about 60 per cent foreign demand on the lake to an Engel & Völkers and Nomisma 2025 report; no such figure could be traced and it has been removed. It attributed to Liam Bailey of Knight Frank the view that the outflow of UK wealth to Italy, Monaco and Switzerland is structural; the report says the abolition of the non-dom regime triggered 'meaningful, if undramatic' outflows and that early signs point to incremental movement rather than a surge, and the history of buyer waves on the lake is now labelled a Victaura Research assumption. It said MEF projections expect the EUR 300,000 charge to halve new 24-bis entrants, that 400 to 600 UK-origin entrants arrived in 2024 with 15 to 20 per cent living on Lake Como, and that 1,631 taxpayers were active in 2024; the first is a prudential assumption in the technical report to the 2026 Budget Law and is not used here, no source contains the second, the third was attributed to industry estimates, and the article now gives Corte dei Conti figures of 1,923 beneficiaries in 2024, 1,374 of them principal taxpayers (QuiFinanza, 26 June 2026), and applies the EUR 300,000 charge to residence transfers from 1 January 2026 (idealista, 15 December 2025). It said Article 142 of Legislative Decree 42/2004 protects a 300-metre band around lakes classified of public interest, covering the entire Como shoreline, and makes new construction prohibitive; the band applies by law to lakes, does not apply to certain areas already urbanised in 1985, and the prohibitive effect is now labelled a Victaura Research assumption. It said Corinthia had placed three branded units and named five hotel-only schemes; Corinthia plans three residences in a resort due in late 2028, and the article now names only the EDITION, Ritz-Carlton and Six Senses schemes, whose announcements describe hotels without residences. In the four-market table, the five-year Lake Como figure has been replaced with the 2025 rank. The Zanzibar statute and the sea-level rate have been corrected. The RAK increase of 118 per cent is now described as a rise in transaction value (RAK Municipality). The branded pipeline of 9,000 units is now about 10,000 branded units among more than 34,000 due between 2026 and 2030 (CBRE, H1 2026 review). For Zanzibar, the article cited the Zanzibar Investment Promotion Act 2018 for leasehold tenure and the Tanzania Investment Act 2022 for Strategic Investment Status; the 2018 law was repealed by the Zanzibar Investment Act 2023, which governs Strategic Investment Status, and leasehold tenure rests on the Land Tenure Act 1992 (Rive & Co; Charter Cities Institute). It called Park Hyatt the longest-tenured five-star anchor on the island; this could not be verified and has been removed. It gave Western Indian Ocean sea level rise as 3.5 mm a year, 4 per cent above the global mean; the cited study gives about 3.3 mm a year for the East African large marine ecosystem against a global 3.4 mm (Communications Earth & Environment, 15 December 2025). An erosion rate of 15.6 metres a year and a projection of annual coral bleaching around Zanzibar could not be verified in a source that could be opened, and have been removed.
A sixth review on the same day corrected further points. A review of the passages from the Zanzibar pullquote to the end of the successor lens found errors, some of which the corrections list above had already reported as fixed without their having been fixed. The article gave Wynn's 'modest delay' as disclosed on 8 May 2026 and attributed it to rerouting via Hormuz; the call took place on 7 May 2026, and Craig Billings cited logistical and shipping challenges and said shipments were being rerouted, without naming Hormuz (call transcript, The Motley Fool). It attributed a 118 per cent rise in RAK transactions to the RAK Statistics Centre; the figure is the rise in transaction value to AED 15.08 billion, from RAK Municipality data (Kanebridge News, 14 February 2025). It gave a 39 per cent rise in RAK prices in Q1 2025, a Mondrian sell-out within hours and a CBRE pipeline of more than 9,000 branded units, with the branded share rising from 27 to 54 per cent; none of this is in the sources, and the article now gives CBRE's figure of around 10,000 branded residences among more than 34,000 units due between 2026 and 2030 and H1 2026 price rises of 18.0 per cent for apartments and 7.3 per cent for villas (CBRE, reported by mid-east.info). It gave Macau corrections of 30 to 50 per cent, a 5 per cent annual growth rate for Marina Bay Sands and a 28 per cent consensus projection for RAK from EY, JLL and Colliers; none could be traced, and the Macau base rate is now labelled a Victaura Research assumption. It quoted Cinzia Bianco verbatim calling the UAE 'a front-line state of Gulf politics, not a strategic hedger'; that phrase is not in her ECFR article of 15 May 2026, and the article now quotes her words on the UAE deciding to retaliate and her view that the war is a Zeitenwende for the Gulf. It referred to an early May 'Fujairah port attack' without dating the state of the war; it now reports the 4 May strike on the Fujairah Petroleum Industries Zone as the first on the UAE since the 8 April ceasefire (Al Jazeera, 4 May 2026) and states that as of 26 September 2026 no ceasefire is in force and Hormuz shipping remains partially disrupted (GlobalSecurity.org). It said Dubai prices fell about 20 per cent year on year in March 2026; the value of residential sales fell nearly 20 per cent from February, to USD 10.1 billion, while average prices fell around 4 to 5 per cent (REIDIN data, reported by Business Upturn). It cited 'Federal Law 11/2021' for RAK freehold zones and described freehold as mortgage-eligible; Law No. 11 of 2021 is a Ras Al Khaimah law on the Real Estate Registry issued by the Ruler (Lexis Middle East), and the mortgage point has been removed. It gave the UHNW share of Cerulli's USD 124 trillion as USD 25 to 35 trillion; Cerulli attributes USD 62 trillion to high-net-worth and ultra-high-net-worth households together and gives no separate UHNW figure. It gave Asia-Pacific transfers of USD 5 to 6 trillion by 2030, 60 per cent from UHNW families, and a Hurun figure of USD 11.8 trillion for China; the article now cites UBS's estimate of about USD 11 trillion across Asia-Pacific over 20 to 30 years (South China Morning Post, 12 May 2026) and the Bank of East Asia and Hurun figure of USD 11.33 trillion over 30 years (Jing Daily, July 2026). It said wellness led the lifestyle priorities of Knight Frank's NextGen sample at 24 per cent; that figure applies to respondents with household income above USD 1 million. It gave Wharton and BNP Paribas ESG figures that could not be traced; they have been removed, and the Stanford finding is now given with its figures (44 per cent in 2022, 11 per cent in autumn 2024). It gave sea level projections of 13 to 35 centimetres by 2050 for Lombok, said Aman Villas at Nusa Dua were sold out and listed 15 Anantara Ubud residences; none could be verified in a source that could be opened, and all three have been removed. It applied the US step-up in basis to Lake Como and the Côte d'Azur without qualification; the rule applies to property inherited from US taxpayers, and the timing of the supply unlock is now labelled a Victaura Research assumption. A pullquote attributed to Rebecca Gooch of Deloitte Private had no traceable source and is now attributed to Victaura Research.
A seventh review on the same day corrected further points. A review of the considerations for capital allocators and of the methodology section corrected further points. The article said CARF and DAC8 were in force across 76 reporting jurisdictions from 1 January 2026 and that the opacity model would close by about 2028; the OECD list shows 46 jurisdictions collecting data from that date for first exchanges in 2027, with 27 more committed for 2028 and 4 for 2029 (OECD Global Forum, 14 September 2026), and the timing of the close is now labelled a Victaura Research assumption. It described Hak Milik as constitutional; the restriction to Indonesian citizens is in Article 21 of the Basic Agrarian Law of 1960. It said four or five luxury operators chose hotel-only on Lake Como; the article documents three. It said the post-reform HMRC series was expected in early 2027 and gave the status of the Henley audit as of 28 May 2026; the government has said only that accurate estimates will follow in 2027 (The National, 31 July 2026), the audit named no auditor (Spear's, 19 August 2025) and Henley's 2026 report of 16 June 2026 gives no migration count (Henley & Partners). It gave Asian transfers of USD 5 to 6 trillion by 2030; no source contains this, and the article now cites UBS's estimate of about USD 11 trillion across Asia-Pacific over 20 to 30 years (South China Morning Post, 12 May 2026). It said the Bernstein, Gustafson and Lewis discount showed climate risk priced into luxury and had been reinforced by insurance repricing; the paper finds about 7% on US homes exposed to sea level rise, and the insurance claim has been removed. The methodology section said all figures came from primary documents, that UK figures relied on industry estimates and an HMRC release of 7 August 2025 with 24-bis data as a proxy, gave a 24-bis series from 94 taxpayers in 2017 to 1,631 in 2024, and listed paraphrases of Helen Miller, Mark Bou Mansour, Liam Bailey, Rebecca Gooch, Daron Acemoglu, James Hansen and a 2025 Corte dei Conti report; it now states that secondary sources are named as such, that UK figures come from the HMRC release of 30 July 2026, that the 24-bis figures are the Corte dei Conti's 1,923 beneficiaries in 2024 (QuiFinanza, 26 June 2026) while the earlier series is not used, and that the untraceable paraphrases have been removed and the Corte dei Conti finding dates from June 2024.
An eighth review on the same day corrected further points. A review of the headline, summary and key takeaways found figures that the corrections in the body had not reached. The summary and takeaways gave an effective UK outflow of 1,800 to 3,800 from CenTax and Companies House data, with Italy taking 15 to 20 per cent; no source contains these figures, and they now say that HMRC counted 81,900 non-domiciled and deemed-domiciled taxpayers in 2024-25 and that estimates of post-reform departures will only follow in 2027 (HMRC, 30 July 2026, reported by The National). This removes a pillar of the original thesis: the article can say that Henley's projection is unreliable, not that the real UK outflow is far smaller. They said Henley's 142,000 figure failed an independent forensic test and that a peer review had not concluded; Tax Policy Associates put one digit pattern at about a 1-in-240,000 chance (27 July 2025), Henley announced an audit in August 2025 without naming an auditor (Spear's, 19 August 2025), and its 2026 report of 16 June 2026 gives no migration count. They said the 24-bis regime grew from 94 taxpayers in 2017 to 1,631 in 2024; Corte dei Conti figures give 1,923 beneficiaries in 2024, 1,374 of them principal taxpayers (QuiFinanza, 26 June 2026), and the EUR 300,000 charge applies to residence transfers from 1 January 2026 (idealista, 15 December 2025). They gave Hong Kong and Switzerland at USD 2.95 and 2.94 trillion; BCG gives about USD 2.9 trillion for Hong Kong and no Swiss figure (BCG, 27 May 2026). They said CARF and DAC8 went live across 76 jurisdictions; the OECD list shows 46 collecting data from 1 January 2026, with 27 more committed for 2028 and 4 for 2029 (OECD, 14 September 2026), and the timing of the close of the opacity model is now labelled a Victaura Research assumption. They described the UAE as a 'front-line state'; the ECFR article by Cinzia Bianco does not contain the phrase, and the takeaway now dates the 4 May Fujairah strike (Al Jazeera, 4 May 2026) and states that as of 26 September 2026 no ceasefire is in force (GlobalSecurity.org). The Knight Frank price changes are now dated to 2025, and the Dubai forecast is dated to November 2025. In the reference list, the OBR, HMRC, Corte dei Conti, ECFR and Wynn entries have been relabelled with their correct documents and dates.
From Victaura
- Our Approach: Location, Timing, Execution
- Modern Villa on Lake Como (Pognana Lario)
- Secret Zanzibar Hotel & Villas (Nungwi)
- Gili Air Villas (boutique development, Hak Pakai)
- Ras Al Khaimah Residential Compounds (off-plan capital position, Al Marjan Island)
- Insights: Scarcity as Value Protection
- Insights: Branded Residences in the Luxury Market
- Invest with Victaura
References
- Knight Frank, The Wealth Report 2026 (PIRI 100)
- Boston Consulting Group, Global Wealth Report 2026 (27 May 2026)
- Capgemini, World Wealth Report 2025
- Henley & Partners, Private Wealth Migration Report 2025 (directional)
- Tax Policy Associates (Dan Neidle), forensic critique of Henley methodology, 2025
- Office for Budget Responsibility, Economic and fiscal outlook, March 2026 (the £33.9 billion non-dom costing cited in the text is from the OBR's January 2025 supplementary release, as summarised by Tax Policy Associates)
- HMRC, Statistics on non-domiciled taxpayers in the UK (last updated 30 July 2026, covering 2024-25)
- World Justice Project, Rule of Law Index 2025
- Fraser Institute, Economic Freedom of the World 2025
- Heritage Foundation, Index of Economic Freedom 2025
- ND-GAIN, Notre Dame Global Adaptation Initiative Country Index
- V-Dem Institute, Democracy Report 2025 and 2026
- OECD, CARF and DAC8 commitments and timeline
- Cerulli Associates, USD 124 trillion intergenerational wealth transfer through 2048
- UBS, Billionaire Ambitions Report 2025
- Knight Frank, NextGen Survey 2025 (within The Wealth Report 2025)
- Corte dei Conti, Relazione sul rendiconto generale dello Stato, June 2024 (observations on the substitute tax, as reported by Pagella Politica)
- Italian Ministry of Economy and Finance (MEF), website
- Cinzia Bianco, The postwar UAE and the remaking of Gulf politics, ECFR (15 May 2026)
- Wynn Resorts, first quarter 2026 results release (7 May 2026)
- Bernstein, Gustafson & Lewis (2019), Journal of Financial Economics, SLR-exposed coastal property discount
- Swiss Re Institute, sigma reports 2025 to 2026
- Eerste Kamer, Wet werkelijk rendement box 3, dossier 36.748 (status read 27 September 2026)
- Eerste Kamer, plenary record of 30 June 2026, Wet werkelijk rendement box 3 (vote on the bill deferred until the announced novelle is debated)
- Minister and State Secretary of Finance, letter to the Eerste Kamer on progress of the Box 3 adjustment, 14 September 2026 (Kamerstuk 36.748, Q)
- Mercurius Vermogensbeheer, Prinsjesdag 2026: box 3 blijft nog even bij het oude (19 September 2026, secondary source)
- OECD Global Forum, Jurisdictions committed to implement the CARF (list updated 14 September 2026)
- Henley & Partners, Private Wealth Migration Report 2025, press release (24 June 2025)
- Henley & Partners, Private Wealth Migration Report 2026, press release (16 June 2026)
- Spear's, Controversial millionaire migration report subject to independent review (19 August 2025)
- The National, More than 1,000 non-doms left UK before tax reform took effect (31 July 2026, on HMRC release of 30 July 2026)
- Tax Policy Associates, The £34bn cost of Reform UK's Britannia card proposal (OBR January 2025 non-dom costing)
- Tax Justice Network, HMRC data debunks UK non-dom exodus claims, FT reports (14 August 2025)
- Pagella Politica, La flat tax sui Paperoni resta un mistero (19 August 2024)
- MilanoFinanza, Flat tax, Italia nuova casa dei Paperoni grazie ai regimi agevolati (22 October 2025)
- QuiFinanza, Flat tax redditi esteri, la Corte dei Conti frena (26 June 2026)
- Knight Frank, The Wealth Report 2026 (full PDF, PIRI 100 databank)
- Khaleej Times, Dubai's prime property market to grow 3% in 2026 (24 November 2025)
- Institute of Economic Affairs, Economic Freedom of the World: 2025 Annual Report
- World Justice Project, The United Arab Emirates ranks 37 out of 143 in the WJP Rule of Law Index 2025 (28 October 2025)
- Edelman, 2026 Edelman Trust Barometer press release (18 January 2026)
- Climate Adaptation Platform, ND-GAIN rankings (scores updated June 2025)
- Opalesque, Singapore confirms over 2,000 tax-incentivised single family offices in parliamentary reply (6 August 2026)
- Al Jazeera, UAE reports missile and drone strikes incoming from Iran (4 May 2026)
- Wikipedia, 2026 Iran war ceasefire (timeline to the 8 July 2026 collapse)
- GlobalSecurity.org, Iran War 2026 operational update (status read 26 September 2026)
- Skift, Wynn Al Marjan Island faces 'modest delay' (8 May 2026)
- Business Upturn, Dubai home sales fall nearly 20% in March 2026 to USD 10.1 billion (REIDIN data)
- Blick, Immer weniger Pauschalbesteuerte, aber trotzdem mehr Steuereinnahmen (24 August 2026)
- Swiss Federal Department of Finance, Lump-sum taxation
- Repubblica e Cantone Ticino, Dati riferiti alle persone imposte secondo il dispendio (26 September 2025)
- VitalLaw, Greece planning improvements to non-dom regime (30 June 2025)
- OECS, Caribbean countries pressing forward with the implementation of the Memorandum of Agreement on citizenship by investment programmes
- Euronews, French PM Bayrou accuses Rome of tax dumping, Italians respond (1 September 2025)
- World Justice Project, The Netherlands ranks 9 out of 143 in the WJP Rule of Law Index 2025 (28 October 2025)
- World Justice Project, Singapore ranks 16 out of 143 in the WJP Rule of Law Index 2025 (28 October 2025)
- Statranker, Top 100 countries by Rule of Law Index 2025 (WJP scores, secondary source)
- Heritage Foundation, Highlights of the 2025 Index of Economic Freedom
- Royal Swedish Academy of Sciences, The Prize in Economic Sciences 2024
- Claims Journal, Swiss Re: wildfires, storms, floods account for 92% of global insured losses (24 March 2026)
- Copernicus C3S, 2025 was the third hottest year on record (14 January 2026)
- Hansen et al., Global warming in the pipeline, Oxford Open Climate Change (2023)
- Clean Creatives, Edelman
- Afrobarometer Working Paper 176, The autocratic trust bias: politically sensitive survey items and self-censorship (Tannenberg)
- Reporters Without Borders, United Arab Emirates country page (World Press Freedom Index 2026)
- Human Rights Watch, UAE: Unfair mass trial convictions upheld (4 March 2025)
- V-Dem Institute, Democracy Report 2025: 25 Years of Autocratization
- V-Dem Institute, Democratic backsliding reaches Western democracies (Democracy Report 2026 press release, 17 March 2026)
- Harvard Department of Government, Levitsky and Ziblatt publish article in Foreign Affairs (The Price of American Authoritarianism, 16 December 2025)
- NL Times, Outgoing PM Dick Schoof reflects after final Cabinet meeting (13 February 2026)
- KPMG, EC launches infringement procedures on DAC9 and DAC8 (February 2026)
- Y-Axis, Singapore ranks 6th in the Global Peace Index 2025 (secondary source)
- Monetary Authority of Singapore, MAS takes regulatory actions against 9 financial institutions for AML-related breaches (4 July 2025)
- World Justice Project, Italy ranks 34 out of 143 in the WJP Rule of Law Index 2025 (28 October 2025)
- World Justice Project, Portugal ranks 29 out of 143 in the WJP Rule of Law Index 2025 (28 October 2025)
- World Justice Project, Greece ranks 48 out of 143 in the WJP Rule of Law Index 2025 (28 October 2025)
- Statranker, Top 100 countries by Democracy Index (EIU 2024 values, secondary source)
- Wikipedia, The Economist Democracy Index (2025 edition table)
- Wikipedia, 2026 Italian constitutional referendum (results)
- Eurasia Group, Top Risks 2026 (5 January 2026)
- Time Out, How the US ranked on the 2025 Global Peace Index (30 June 2025)
- Property Investor Today, London prime sales rise and fall (August 2026, Knight Frank PCL data)
- Knight Frank, London falls behind as global prime sales gather pace (February 2026)
- Gulf News, Over 40,000 apply for Saudi Premium Residency as kingdom expands scheme
- Wikipedia, The Line, Saudi Arabia (suspension of 16 September 2025 and PIF write-down)
- Xinhua, OCA: 2029 Asian Winter Games moved to Almaty (3 February 2026)
- Gulf News, 158,000 golden visas issued in Dubai in 2023
- mid-east.info, RAK Real Estate Market Review H1 2026 (CBRE Middle East)
- Rive & Co, Unlocking Zanzibar's investment potential (Zanzibar Investment Act 2023, Strategic Investment Status)
- InvestmentNews, Family offices step up governance and global reach in 2025 (KPMG and Agreus benchmark report)
- DIFC, DIFC strengthens global family wealth hub status with new programmes and partnerships (November 2025)
- ADGM, ADGM is the MENA region's largest IFC with 11,128 active licences at the end of H1 2025
- WikiMilano, Family office in Italia crescono del 10% nel 2025 (Osservatorio Family Office, Politecnico di Milano)
- Caproasia, UBS Global Family Office Report 2025 (asset allocation 2024)
- TanzaniaInvest, Zanzibar tourist arrivals increase by 15.4% in 2024 to 736,755 (OCGS Zanzibar Annual Tourism Report 2024, 16 April 2025)
- Brocardi, Codice dei beni culturali e del paesaggio, Art. 142, Aree tutelate per legge
- idealista, Flat tax aumenta a 300.000 euro: ecco cosa cambia dal 2026 (15 December 2025)
- Hospitality Net, Corinthia Hotels, RoundShield and Kervis announce luxury development in Lake Como, opening 2028
- The Lake Como EDITION, opening announcement by EDITION Hotels (12 November 2025, as published by Hotel Online): 148 rooms, preview opening in September 2025, grand opening in March 2026
- One Mile at a Time, Ritz-Carlton Lake Como Bellagio opening 2026 (28 February 2023)
- TOP HOTEL NEWS, Six Senses adds Italian sites (25 October 2024)
- Rive & Co, Registering a land interest in Zanzibar: a guide for foreign investors (leasehold and condominium)
- Charter Cities Institute, A policy evaluation of the 2018 and 2023 Zanzibar investment laws (May 2024)
- Hyatt, Park Hyatt Zanzibar officially opens and marks first Hyatt hotel in Zanzibar (12 March 2015)
- Anantara Zanzibar Resort & Residences, project website (opening 2027)
- Kemgang Ghomsi et al., Accelerating sea level rise in Africa and its large marine ecosystems since the 1990s, Communications Earth & Environment (15 December 2025)
- Climate Watch Zanzibar, Sea level rise and coastal erosion
- The Conversation, More than half of Indonesia's protected coral areas look set to suffer severe bleaching every year by 2044 (22 November 2023, on De Clippele et al.)
- Kanebridge News, Ras Al Khaimah's real estate transactions soar 118% to AED 15.08 billion in 2024 (RAK Municipality data, 14 February 2025)
- The Bali Sun, Bali targets 6.5 million international tourist arrivals in 2025 (6.3 million in 2024, Bali Provincial Tourism Office, 3 January 2025)
- Kontan, Tertinggi sejak pandemi, kunjungan wisman sepanjang 2024 tembus 13,9 juta (BPS data)
- Mandarin Oriental, Mandarin Oriental to open a luxury resort and branded residences in Bali (19 July 2024)
- Wynn Resorts, Wynn Resorts announces receipt of gaming operator license for Wynn Al Marjan Island (4 October 2024)
- The Motley Fool, Wynn Resorts Q1 2026 earnings call transcript (call of 7 May 2026)
- Lexis Middle East, Ras Al Khaimah Law No. 11 of 2021 on the Real Estate Registry
- Will & Rich, Can foreigners buy property in Ras Al Khaimah? (designated freehold areas, secondary source)
- Legal Information Institute, 26 U.S. Code § 1014, Basis of property acquired from a decedent
- South China Morning Post, Wealth shift: Chinese heirs take control sooner as US$11 trillion set to change hands (12 May 2026, UBS estimate)
- Jing Daily, China's wealthy families to pass on USD 3.09 trillion in next decade (Bank of East Asia and Hurun Research, July 2026)
- Private Jet Card Comparisons, Private jets are top-of-mind for NextGen HNWs: Knight Frank (6 March 2025, Wealth Report 2025 NextGen survey)
- phys.org, Young people are losing interest in sustainable investing, survey shows (Stanford GSB, January 2025)
- Normattiva, Law 30 December 2025, n. 199, Article 1, paragraphs 25 and 26
- Assonime, Towards Italy. L'Italia e l'attrazione di HNWI, manager e talenti, No. 7/2026 (PDF copy on sipotra.it)
- Wynn Resorts, second quarter 2026 results release (4 August 2026)
- AGBI, Iran war drives up costs at Wynn's UAE casino project (5 August 2026)
The information on this website is provided for informational purposes only and does not constitute an offer, solicitation, or financial advice. Indicated returns are estimates and are not guaranteed; past performance is not indicative of future results. Capital invested is at risk.
Considering an allocation to luxury real estate in the locations we operate? Speak to us about our current and upcoming projects.
Speak to Victaura →Related insights
Market Views
Wealth Migration: After the Count Was Dropped
Henley & Partners' Private Wealth Migration Report 2026, published 16 June 2026, drops its long-running millionaire count and introduces a twelve-dimension Global Wealth Mobility Framework instead, scoring the UAE at 85.3 and the UK at 68.3. The new score is explicitly not a measure of flows. What remains checkable are national records: HMRC's count of 81,900 non-domiciled and deemed-domiciled UK taxpayers and Italy's 1,923 Article 24-bis beneficiaries.
Market Views
Dubai to Milan: The Relocation Story, Tested
Since March 2026 the international press has told a story of wealthy residents leaving Dubai for Milan. This article separates the story from the measurement. Little is consolidated today, the statistics that would settle it arrive in 2027, and the indirect signals in Milan and on Lake Como are mixed. What can be said now is narrower than the headlines, and more useful to an allocator.
Market Views
Lake Como Prices: What the Official Data Shows
Lake Como OMI quotations from the Agenzia delle Entrate cover seven shore comuni at 670 to 3,060 euro per square metre for apartments (directional), while Knight Frank prices four- or five-bedroom villas at US$14 million to US$18 million (broker-reported). The two sources describe different objects. This note shows why the official band stops short of the lakefront villa, and what would join the two.